BUSINESS
Vietnam Banks Bid 9% Deposits to Fund Year-End Loans
Twelve banks lifted savings rates in November 2025 to fund loans, while 9% prints sat behind VND2,000 billion tickets and later crushed margins.

Twelve Vietnamese banks raised savings rates in the first half of November 2025 as they hunted deposits for a year-end lending push. The public fight looked like a household passbook race. The price that actually moved the money sat on a different ticket.
PVcomBank was already listing 9% a year on 12- and 13-month money, but only on new counter balances from VND2,000 billion. Ordinary online money at the same bank paid 5.8%. That split, not the 0.2-point tweaks on one-month money, is what the rush left behind.
Twelve Banks Moved Before Mid-November
KienlongBank broke a freeze of nearly eight months on November 11, lifting 1- to 4-month and 6- to 7-month online rates by 0.2 percentage points and cutting 8- to 9-month money by 0.1 point. Twelve-month online money printed 5.5%. LPBank had moved a day earlier, adding 0.3 points on 1- to 5-month terms and 0.2 points on 6- to 11-month terms, taking those lines to 3.9-4.2% and 5.3%.
Techcombank’s November 12 online board put 1- to 2-month money at 3.95% and jammed the 3-month line into the legal ceiling at 4.75%. Twelve-month money went to 5.75%. VPBank had already added 0.3 points against October on the counter, taking one-month money to 4.2%. By November 30 its 3-month line sat at 4.75% as well, 0.65 points above October 31, with 12-month money at 5.8%.
THE NOVEMBER RATE MOVES
- November 5, 2025: VPBank lifts online terms by 0.3 points; one-month money prints 4.3% on that board.
- November 10, 2025: LPBank raises 1- to 5-month online rates by 0.3 points and 6- to 11-month rates by 0.2 points; 12- to 16-month money stays at 5.4%.
- November 11, 2025: KienlongBank ends an eight-month freeze with a 0.2-point rise on short tenors and a 0.1-point cut on 8- to 9-month money.
- November 12, 2025: Techcombank takes 3-month online deposits to 4.75%, the cap for terms under six months.
- November 14, 2025: Cake by VPBank lists 6.5% on 12- to 36-month money with no jumbo minimum, the highest clean board over six months that week.
- November 20, 2025: OCB becomes the 19th bank in the month to reprice; short tenors at several private lenders sit on the 4.75% cap.
- November 30, 2025: Twenty banks have raised deposit rates during the month, including Sacombank, VPBank, MB, HDBank, Techcombank, LPBank, KienlongBank and PVcomBank.
BVBank ran a “10 Golden Days” offer up to 6.8% on 12-month online money and sold online certificates of deposit up to 6.3% on a 15-month tenor. LPBank paid 6.5% at the end of term on balances from VND300 billion. The first-half count of 12 banks was only the opening bid. By month-end the wave had reached 20 names, almost all of them joint-stock lenders.
The 9% Rate Needs VND2,000 Billion
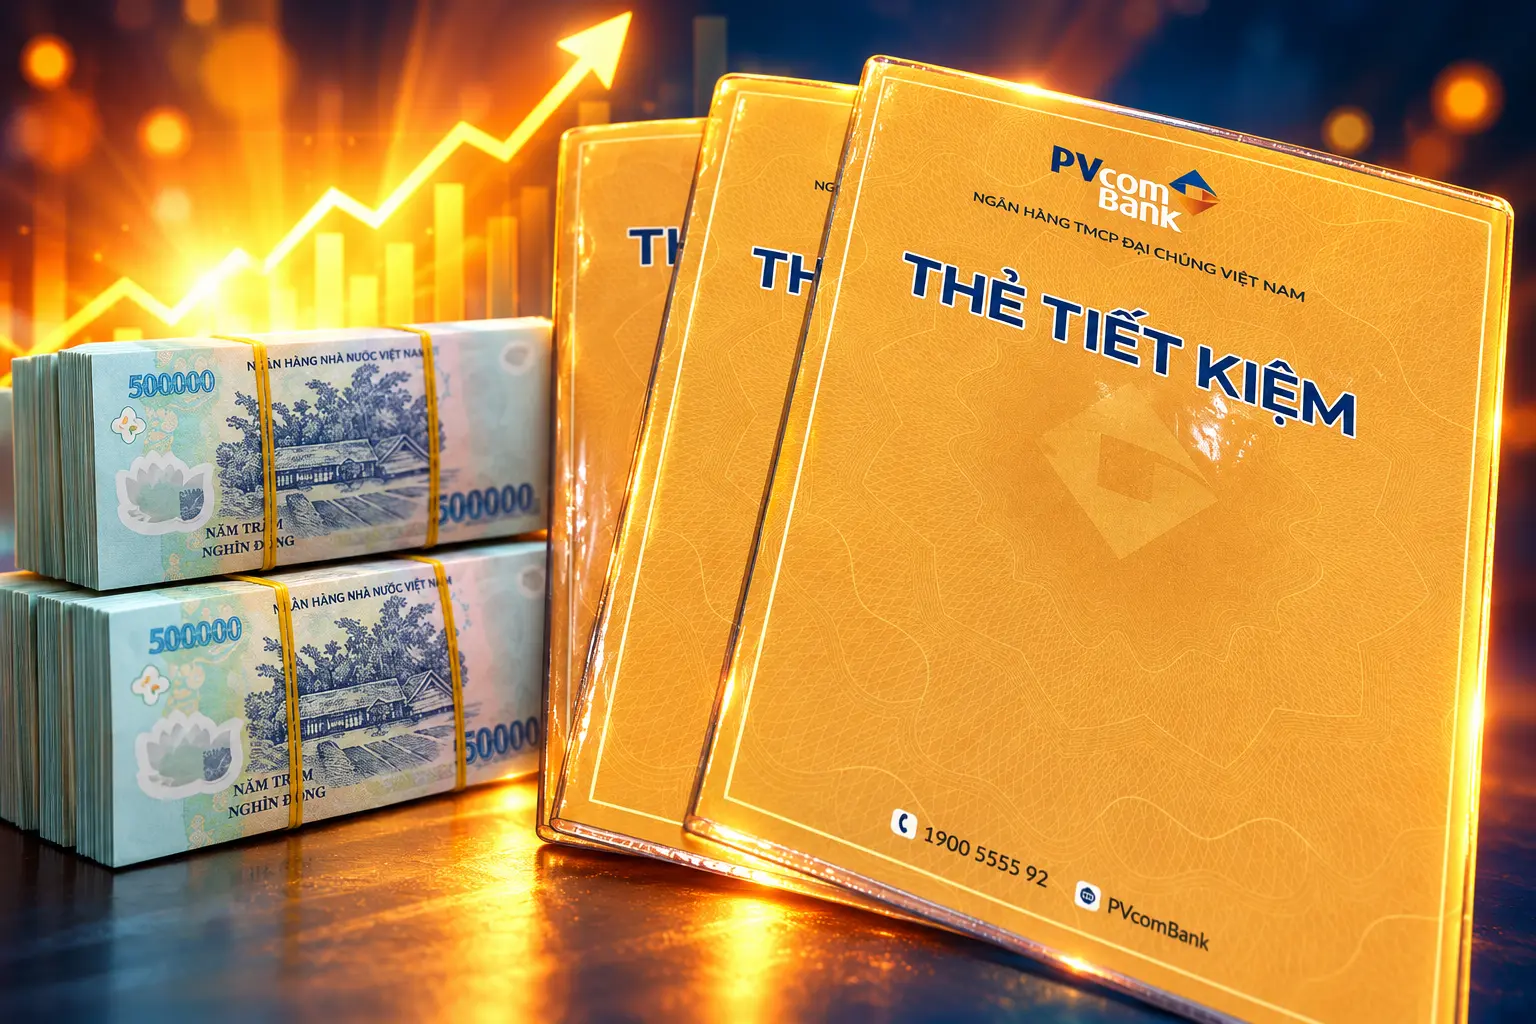
A November 28 survey of nearly 30 banks put PVcomBank at the top of the 13-month board at 9% a year. The catch was mechanical. The rate applied at the counter to newly opened balances from VND2,000 billion, two trillion dong. Under ordinary rules the same bank listed 5.5% at the counter and 5.8% online.
HDBank printed 8.1% on 13-month money if the customer kept at least VND300 billion in the account. At the counter, ordinary 13-month money paid 5.9%; online it paid 6.0%. Cake’s 6.5% on 12- to 36-month deposits was the rare high print that did not hide behind a billion-dong floor.
JUMBO TICKETS VERSUS THE COUNTER
| Bank and product | Term | Headline rate | Ordinary rate beside it |
|---|---|---|---|
| PVcomBank, new counter balance from VND2,000 billion (Nov. 28, 2025) | 12-13 months | 9% | 5.5% counter, 5.8% online |
| HDBank, minimum VND300 billion (Nov. 28, 2025) | 13 months | 8.1% | 5.9% counter, 6.0% online |
| Cake by VPBank, no jumbo floor (Nov. 14, 2025) | 12-36 months | 6.5% | Same listed line |
| PVcomBank Đại Chúng, new counter from VND2,000 billion (sheet in force Apr. 11, 2026) | 12 and 13 months | 10.00% | 5.30% (12-month*) and 5.50% (13-month*) below that floor |
That 10.00% line is not a rumour. PVcomBank’s own personal-deposit sheet, in force from April 11, 2026, still prints 10% on 12- and 13-month terms for the Đại Chúng product at the counter when the new balance starts at VND2,000 billion, and 5.30% or 5.50% when it does not. The gap is 4.70 points on the 12-month line. Household savers were never in that auction.
Vietcombank Still Paid 1.6% on One-Month Money
While private boards ran at the cap, the four state lenders stayed out. A November 20 online board still had Vietcombank at 1.6% on one-month money and 4.6% on 12 months. Agribank’s 12-month line was 4.8%, the high among the state group, and it had sat there for about six months. VietinBank printed 2.0% on one month and 4.7% on 12 months.
Vikki Bank, on the same day, listed 4.7% on one month and 6.3% on 12 months. Bac A Bank had 6.2% on six months and 6.3% on 12 months. Techcombank’s 3-month line was already at 4.75%. One-month money at Vikki paid 3.1 points more than Vietcombank.
STATE BANKS AND PRIVATE LENDERS ON NOVEMBER 20
| Bank | 1 month | 3 months | 6 months | 12 months |
|---|---|---|---|---|
| Vietcombank | 1.6% | 1.9% | 2.9% | 4.6% |
| Agribank | 2.4% | 3.0% | 3.7% | 4.8% |
| VietinBank | 2.0% | 2.3% | 3.3% | 4.7% |
| Techcombank | 3.95% | 4.75% | 5.45% | 5.75% |
| HDBank | 4.2% | 4.3% | 5.5% | 5.8% |
| Vikki Bank | 4.7% | 4.7% | 6.1% | 6.3% |
| Bac A Bank | 4.55% | 4.55% | 6.2% | 6.3% |
The state group could fund a lending season on cheap current accounts and a loyal deposit base. Joint-stock banks that were running loan books harder had to buy term money, then buy it again when those terms rolled. Several of them pushed tenors under six months onto the legal ceiling because that was the only short-term price the rule still allowed.
Credit Finished 2025 at 19.01%
The deposit bid had a purpose. In November, lenders and economists were still talking about credit growth of 18-20% for 2025. Nguyen Xuan Thanh of the Fulbright School of Public Policy and Management had put the figure needed for an 8% GDP year at about 19-20%. MB General Director Pham Nhu Anh said his bank was aiming for 25-30% loan growth, driven by retail and SME books.
State Bank of Vietnam Deputy Governor Pham Thanh Ha, at a December 29 briefing in Hanoi, said the central bank had opened 2025 with a system target of around 16% and then adjusted with the economy. Year-end figures from the SBV show outstanding credit at VND18.58 quadrillion on December 31, 2025, up 19.01% from the end of 2024. The original 16% target was beaten by 3.01 points. The loans arrived. So did the funding bill.
THE 2025 CREDIT PRINT
- Opening target: The SBV set system credit growth around 16% at the start of 2025, with room to adjust.
- Year-end stock: Outstanding credit reached VND18.58 quadrillion on December 31, 2025, up 19.01%.
- November talk: Banks and economists spent November treating 18-20% as the live range for the year.
- 2026 instruction: The SBV later set a system target around 15% for 2026.
Ha said policy rates were held so banks could still draw cheap central-bank money, and that credit was steered toward production, agriculture, manufacturing and trade. Wholesale and retail remained the largest slice of the book, at 22.24% of outstanding loans by the end of October 2025. Lending rates did not stay still. ACB’s preferential two-year loan rate moved from 6% to 8% a year in November, and VPBank’s floating rate moved from 12% to 14%.
Why 13-Month Deposits Sit Outside the Cap
Short-term dong is not a free market. Decision 2411/QD-NHNN, issued November 1, 2024 under Circular 48/2024/TT-NHNN, sets a 4.75% cap on deposits under six months. Demand money and terms below one month sit at 0.5%. People’s Credit Funds and microfinance institutions may pay 5.25% on the short tenors. Dollar deposits are capped at 0%. From six months up, each bank sets its own price against supply and demand.
That is why 3-month boards piled onto 4.75% in November, and why 13-month tickets became the place to pay 8% or 9% without breaking the short-term rule. A 13-month term is long enough to leave the cap and short enough that a corporate treasurer can still live with the lockup. The refinancing rate has sat at 4.5% since mid-2023, so the ceiling on short deposits is only 0.25 points above the policy rate. When loan demand runs hotter than deposit inflows, the fight moves to uncapped tenors and to private deals off the published board.
Foreign-exchange pressure during the import season was part of the November explanation inside the banks. Ha said the SBV used its tools to keep the FX market orderly while it held policy rates. The deposit war did the rest of the work on the dong book.
A 10-Year Low on Net Interest Margins
By September 2026 the extra loans were on the books and so was the cost of keeping them funded. ACBS, at a September 25 briefing in Hanoi, put the system loan-to-deposit ratio on dong deposits at a record 110% after three years of heavy credit growth. Most customer deposits sit inside one year, with 70% in the three- to six-month band and only 15-20% beyond 12 months. When those deposits mature, they reprice at the new, higher board.
High interest rates and an LDR reaching 110 per cent mean costs are rising faster than interest income, causing NIM to decline. The banking system’s NIM is now only around 2.9 per cent, the lowest level in 10 years.
ACBS analyst, Data Talk briefing, Hanoi, September 25, 2026
That 2.9% figure is the hangover from the 19.01% credit year, not a separate shock. TCBS, in its second-quarter 2026 banking note, had standalone NIM at 3.14%, up from 2.99% in the first quarter but still below 3.24% in the second quarter of 2025. Asset yields rose, just not as fast as liabilities: the annualised yield on interest-earning assets reached 7.64%, while the cost of funds up 106 bps year on year sat at 4.80%.
THE BILL ON THE LIABILITY SIDE
- Dong LDR: ACBS put the VND loan-to-deposit ratio at 110%, a record, after three years of fast credit growth.
- Deposit mix: About 70% of customer deposits sit in three- to six-month money; only 15-20% run past 12 months.
- CASA: Only six of 27 joint-stock banks lifted their current-account ratios in the first half of 2026 as savers chased term rates.
- 2026 gap: By August 28, 2026, system credit was up 10.2% at VND20.2 quadrillion, while deposits were up 5.5%.
Cheap current-account money drained as households locked in term rates. Banks that had grown loans faster than deposits leaned on wholesale funds, certificates of deposit and the next retail campaign. Volume still produced profit at many listed lenders. It did not produce a fatter margin.
The Offered Rate Lives Off the Board
The two-price market did not close when the calendar flipped. In August 2026 the SBV’s own high print on six- to 12-month deposits reached 8%, with terms over 24 months at 8.1%. Promotional offers on six-month money ran around 8.5-9.3%. Certificates of deposit and bank bonds paid about 8.7-10%. Average lending rates reached 10.7% in August, nearly two points above the end of 2025.
On September 29, 2026, ACB led a clean 12-month listed board at 7.8%. VPBank was marketing an effective 9.2-9.3% on selected online terms, from balances as small as VND10 million, after a bonus that is not the standard listed line. PVcomBank’s jumbo 10% ticket was still on the official sheet. The listed board and the rate a customer is actually offered have pulled apart, which is what a tight funding market looks like from the inside.
Household savers still choose between state banks in a lower band and private boards that print 7% and higher, while the 9% and 10% lines sit behind ticket sizes no household can meet. Idle dong has kept flowing into passbooks anyway, because gold, stocks and property have felt jumpy in the same stretch. That flow funds the loan book. It does not close the gap between a VND2,000 billion ticket and a standard online term.
The SBV’s 15% credit growth target for 2026 is slower than 2025 on paper. Fitch has still sketched a path near 18% if the growth drive stays hot. Among banks that took on weak lenders, VPBank’s loan book was up 23.2% by late August, HDBank 21.8% and MB 13.2%, against a 10.2% system average. Those are the same names that had to buy deposits in November 2025, and they are the names still paying up as another year-end approaches, with private banks chasing faster loan growth than the state group is willing to match.
The November 2025 scramble did what it was hired to do. Credit closed the year at 19.01%. The price of that print is still on the liability side: a 110% dong LDR, a 2.9% system margin, and a 10% rate that exists for one kind of balance only.
Frequently Asked Questions
What Is the SBV Cap on Deposits Under Six Months?
Decision 2411/QD-NHNN, dated November 1, 2024, caps VND demand deposits and terms below one month at 0.5% a year and caps 1-month to below 6-month deposits at 4.75%. People’s Credit Funds and microfinance institutions may pay 5.25% on those short tenors, and USD deposits are capped at 0% for both individuals and institutions. From six months upward, banks set their own rates.
How Much Did Vietnam’s Bank Credit Grow in 2025?
State Bank figures for December 31, 2025 show outstanding credit at VND18.58 quadrillion, up 19.01% from the end of 2024, after an opening system target of around 16%. In absolute terms the book added VND2.97 quadrillion during 2025. A 15% target for 2026 implied about VND2.787 quadrillion of new credit, VND183 trillion less than the 2025 flow.
Who Can Get PVcomBank’s 9% or 10% Savings Rate?
The top print is a counter product on newly opened 12- and 13-month Đại Chúng balances from VND2,000 billion, not a running mix of smaller accounts and not an online rate. On November 28, 2025 that line was 9%; the sheet in force from April 11, 2026 prints 10.00%. Balances below that floor on the same terms paid 5.30% (12-month*) and 5.50% (13-month*) on that sheet, and online 12-month money paid 5.60%.
Why Do Vietnamese Banks Push 13-Month Deposit Terms?
Terms from six months up sit outside the 4.75% short-term cap, so a 13-month ticket is the shortest common tenor that can legally pay 8% or 10% without hitting the under-six-month rule. It also keeps the money on the book through a full lending season. That is why jumbo specials cluster on 12- and 13-month money rather than on 3-month deposits, which were already pinned to the ceiling in November 2025.
Disclaimer: This article is news reporting and analysis of Vietnamese bank deposit and credit figures for information only. It is not investment, deposit, tax or lending advice and should not be read as a recommendation to place savings, switch banks or take out a loan. Readers should consult a licensed financial adviser, bank relationship manager or qualified accountant in Vietnam before moving money or signing a deposit or loan contract. Rates, credit quotas and regulatory caps are those published by the banks and the State Bank of Vietnam in the sources dated above and can change without notice.

The Court Revisits the Climate Nuisance Door It Left Open

ChatGPT Now Compiles Live Interfaces With GPT-6

A Tanker Attack Moves the War Into Qatar’s Waters

Personio Buys Circula to Own the DATEV Channel

Bluesky Files for .bsky and Enters the Registry Queue

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Musk’s $914 Billion Lead Is a Public SpaceX Bet

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision
-
 NEWS3 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 BUSINESS5 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 SPORTS4 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-
 ENTERTAINMENT4 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-
 NEWS5 months ago
Singapore’s 3×3 and Surfing Debuts Miss the Medal Stand
-
 NEWS7 months ago
White Sands Footprints Put People in Ice Age New Mexico