BUSINESS
Banks Drew P60.1 Million From the BSP Discount Window
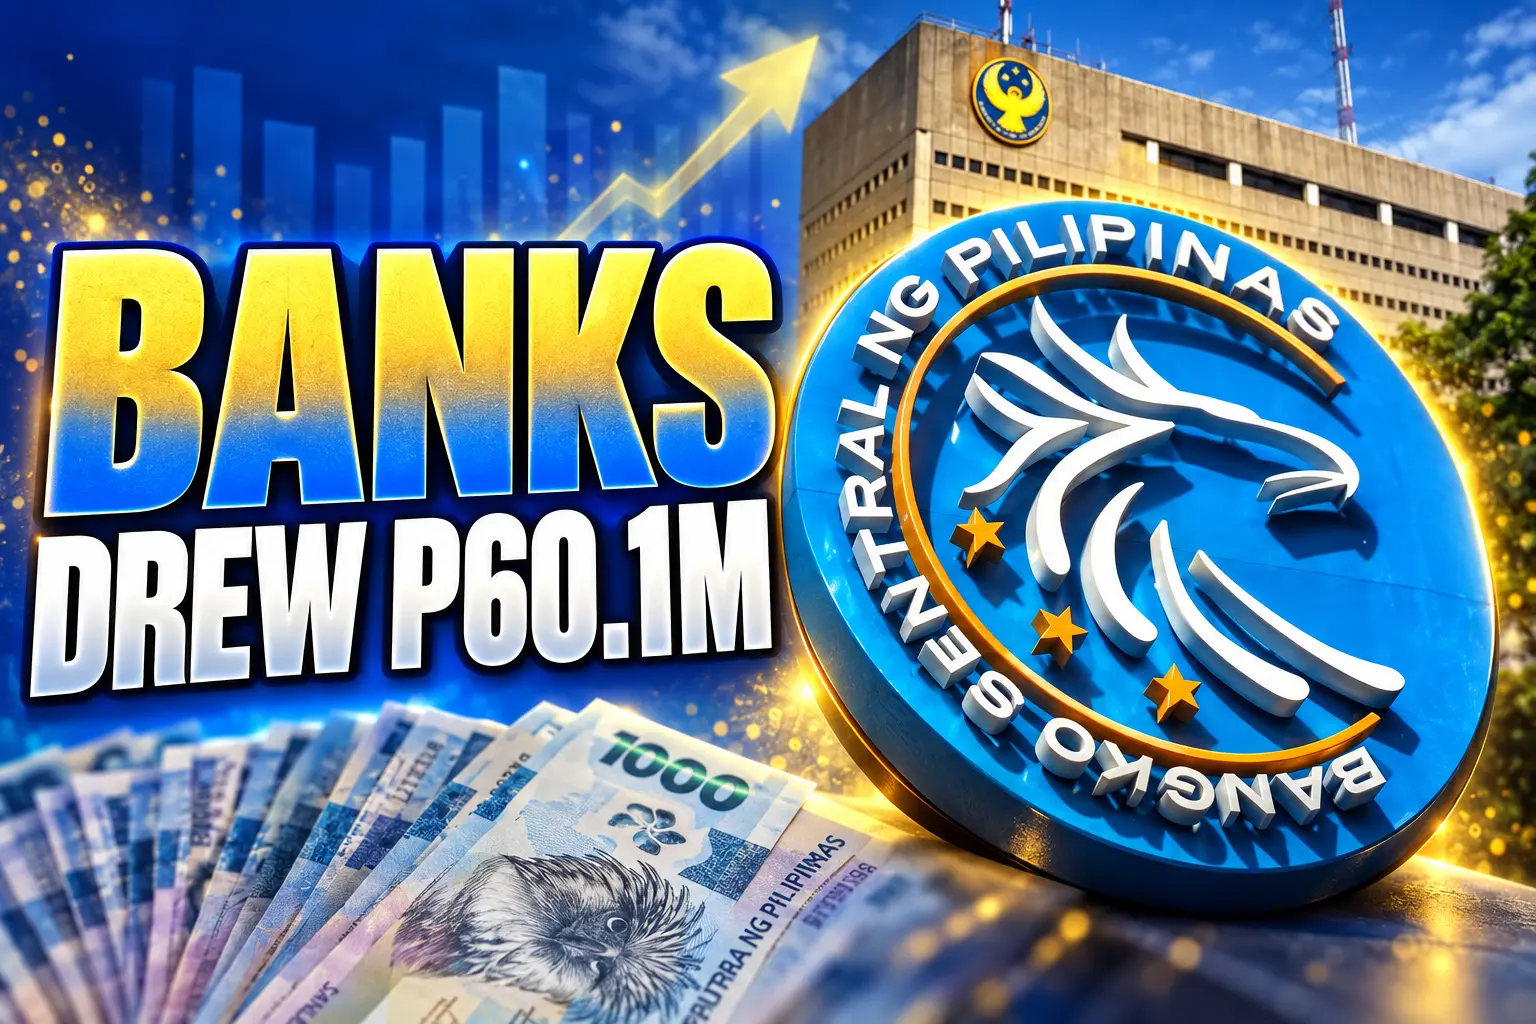
Philippine banks drew P60.1 million from the BSP discount window in 2025 against P348.4 billion of lines, as rural lenders faced an NPL gate on rediscounts.

Philippine banks drew P60.1 million from the Bangko Sentral ng Pilipinas discount window in 2025, the facility’s first full year. Thirty-eight banks held P348.4 billion in approved lines at year-end, and 22 of those names were rural or cooperative lenders.
The cash that moved was a sliver of the unused lines. The central bank spent the same year writing off old loans and collecting from the Philippine Deposit Insurance Corp.
The First-Year Draw Was P60.1 Million
Audited notes released on 25 June 2026 split that P60.1 million in two. Rediscounts of client paper came to PHP16.778 million and were paid back inside 2025. Advances against National Government or BSP securities came to PHP43.286 million and still sat on the books at year-end, due in 2026.
The year-end stock of discount-window credit was PHP43,285,800. In 2024, banks took out no new loans from BSP credit facilities at all. Domestic liquidity, the broad money stock known as M3, still grew 7 percent to P20.108 trillion by December, the slowest pace in four months.
THE 2025 WINDOW IN THREE FIGURES
- Year’s drawings: P60.1 million of rediscounts and advances combined.
- Still outstanding: PHP43.286 million of securities-backed advances at 31 December.
- Approved lines: P348.4 billion across 38 banks, or 0.017 percent drawn.
A window that large, used that little, is a standing offer rather than a rescue. The BSP said as much in its own account of the year.
The BSP provides efficient and responsive credit operations in its role as lender of last resort (LOLR). The discount window facility (DWF) remained available to banks facing temporary liquidity needs throughout the year.
Bangko Sentral ng Pilipinas, 2025 Annual Report
As of 15 December 2025, peso draws of 1 to 90 days cost 5.6433 percent and 91- to 180-day draws cost 5.7866 percent, after a 25-basis-point cut that took the overnight lending facility to 5 percent.
Rural and Cooperative Banks Hold 22 of 38 Lines
The counterparties are not the household names that fund most of M3. Of the 38 banks with live lines, 10 were universal or commercial banks, 22 were rural or cooperative banks, and six were thrift banks.
The peso split of those P348.4 billion lines was not published. What the supervision tables do show is a two-speed loan book. Universal and commercial banks closed 2025 with a 2.80 percent gross non-performing loan ratio. Rural and cooperative banks closed the same year at 8.05 percent, and thrift banks at 6.00 percent.
LINES AND LOAN STRESS AT END-2025
| Bank group | Banks with DWF lines | Gross NPL ratio |
|---|---|---|
| Universal and commercial | 10 | 2.80% |
| Rural and cooperative | 22 | 8.05% |
| Thrift | 6 | 6.00% |
By June 2026 the rural and cooperative ratio had eased to 7.79 percent on a P237.632 billion loan book, against P345.727 billion of deposits. Liquid assets covered 60.83 percent of those deposits, a thicker cash buffer than the system-wide ratio near 47 percent. The small-bank problem is not an empty till. It is a loan book the interbank market does not fund, and a bad-loan ratio the window itself treats as a gate.
Higher NPLs Block Rediscounting of Farm Loans
Circular No. 1202 is blunt on that gate. A bank whose non-performing loan ratio sits above the industry average may use the window only through advances against securities issued by the National Government or the BSP. It cannot rediscount the promissory notes of its own borrowers.
Industry-wide gross NPLs were 3.07 percent at end-2025. Rural and cooperative banks, at 8.05 percent, cleared that bar the wrong way. Their agriculture, forestry and fishing book is the sticky part: P30.464 billion of those loans were still on the June 2026 ledger, with a 10.30 percent non-performing ratio.
Those farm notes are exactly the paper a rediscount window is supposed to take. The NPL rule sends the same banks to a different counter. To draw, they need government or BSP securities to pledge, not a harvest loan. Banks that live on provincial credit often hold less of that paper than a universal bank’s treasury desk.
That is why a roster of 22 rural and cooperative names can dominate the list of approved lines and still leave the window almost untouched. The line is a score on adjusted capital. The draw is a collateral test many of those balance sheets fail on the loan side.
The Central Bank Spent the Year Cleaning Old Credit
The louder movement on the BSP’s own loan book was not the new window. It was the old one being mopped up. Principal collections rose to P1.8 billion from P300.9 million in 2024, nearly six times the prior year’s take. The BSP said P1.5 billion of that came from PDIC’s settlement of financial assistance loans and from recovery of past-due accounts.
Long-overdue loans on the central bank’s books fell 95.2 percent to P219.3 million from P4.5 billion. The BSP said it cleared P2.8 billion of past-due loans during the year. Total outstanding loans and receivables dropped 4.64 percent to P92.4 billion from P96.9 billion.
THE YEAR THE BSP CLEARED OLD LOANS
- 14 April 2025: Settles the financial-assistance loan to Philippine National Bank under a 17 March deal with PDIC, cutting that line by PHP2.972 billion.
- 2025, full year: Writes off PHP1.307 billion of past-due emergency loans and collects another PHP1.485 million on that book.
- 31 December 2025: Emergency loans to rural and cooperative banks still total PHP111.8 million, more than the entire discount-window stock.
- 31 December 2025: Discount-window advances of PHP43.286 million remain the only live DWF balance.
The leftover emergency book for rural and cooperative banks, at PHP111.8 million, still dwarfed the new window. Those emergency credits are a different legal tool, granted at the Monetary Board’s discretion under Section 84 of the charter, not the standing facility banks can tap in the ordinary course.
These loan portfolio clean-up efforts allowed the BSP to refocus its credit operations from resolving legacy exposures to strengthening its core mandate as LOLR.
Bangko Sentral ng Pilipinas, 2025 Annual Report
The annual report also said every loan granted since 2014 had been collected on or before maturity, with the remaining long-past-due accounts still in collection.
How the Discount Window Works
The window replaced the old peso rediscount facility on 2 December 2024 under Circular No. 1202, issued on 24 September 2024 after Monetary Board Resolution No. 1026 dated 5 September 2024. Governor Eli M. Remolona Jr. signed the circular. It is the BSP’s ordinary credit operation under Section 82 of the charter, not an emergency program.
A bank first applies for a one-year line. The size runs from 25 percent to 100 percent of adjusted capital, set by a credit score. The line can be cancelled or cut if supervisors see a change in creditworthiness. Draws can be in pesos, U.S. dollars, or yen, through rediscount of eligible client paper or through advances against national government or BSP securities.
RULES THAT GOVERN A DRAW
- Collateral gate: Banks with NPLs above the industry average may pledge only NG or BSP securities, not client notes.
- Excluded paper: Interbank loans, restructured loans, past-due loans, unsecured loans, personal consumption loans, and loans already funded by other borrowings cannot be rediscounted.
- Price: The peso rate is the overnight lending rate plus a spread the BSP can change with policy.
- Tenor: Availments run up to 180 days from the advance, and not past the maturity of pledged securities.
- Other tests: No past-due obligations to the BSP, and a usable reserve position for the reference week.
Rural and cooperative applicants with a designated depository bank must also file a three-party depository agreement with that bank and the Department of Loans and Credit. That extra pipe is one more reason a small provincial lender can hold a line on paper and still find a draw slow.
The BSP Proposed Annual Tests for Big Banks
On 31 August 2026 the central bank put out a plan to make the same window easier to use. Draft amendments would slim the paperwork, give financially sound banks more room on collateral, and require the country’s systemically important banks to keep a discount-window line and test their access every year. Newly merged banks could get a temporary line of up to 50 percent of adjusted capital for 180 days while reports catch up.
The BSP said the facility “supports confidence in the banking system and contributes to overall financial stability by providing banks with timely access to liquidity when needed.” The sentence is a tell. A window that moved P60.1 million in a P20.108 trillion money stock does not yet do that job in practice. Forcing the largest banks to rehearse a draw is how a central bank kills the stigma of showing up.
The 22 rural and cooperative names already on the roster are not the ones the new test targets. They already enrolled. What they still lack is a path to rediscount the farm and town loans that fill their books, because those books fail the average NPL test. Until that gate moves, the unused P348.4 billion will keep sitting mostly with the lenders who were supposed to need it, and the live balance will keep looking like PHP43.3 million of government paper pledged for a few months.
Frequently Asked Questions
How much did banks borrow from the BSP discount window in 2025?
Availments for the year were P60.1 million, of which PHP16.778 million of rediscounts were repaid before 31 December and PHP43.286 million of advances remained outstanding. That year-end stock was 0.29 percent of the BSP’s loans and advances, a rounding error on a book still dominated by older facilities and the PDIC-related residual.
How does the BSP discount window facility work?
Eligible banks draw against a one-year line through the BSP’s electronic system, in pesos, dollars, or yen, by rediscounting eligible client credit instruments or by taking advances against National Government or BSP securities. Applications go to the Department of Loans and Credit, and a bank with a rejected file may re-apply after three months once it meets the tests.
How many banks had active DWF credit lines at the end of 2025?
Thirty-eight banks held P348.4 billion of lines: 10 universal and commercial banks, 22 rural and cooperative banks, and six thrift banks. The peso share by bank type was not disclosed, so the 22 rural and cooperative names are a headcount, not proof they control most of the money.
Why might a rural bank be limited to securities-backed advances?
Circular No. 1202 bars a bank whose NPL ratio exceeds the industry average from rediscounting client paper. Rural and cooperative banks ended 2025 at 8.05 percent against a 3.07 percent industry print, so the standing rule points them at government or BSP securities even when their own borrowers need the cash.
When did the discount window replace the rediscount facility?
The switch took effect on 2 December 2024 under Circular No. 1202. Existing rediscount lines stayed valid for a year after implementation but could be used only for loan rediscounting, and a bank that wanted advances against government or BSP securities had to apply for a fresh DWF line.

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Sia Sells Half Her Catalog and Keeps the Face

The 7.28% Mortgage Rate Traps Owners and Feeds ARMs

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit

Endgame Encore’s $86 Million Trial for Infinity Vision
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-
 NEWS4 weeks ago
An AI Lung Drug Shifted Biological Age Clocks in Patients