BUSINESS
The 10-Year Yield’s 5% Break Taxes the AI Rally
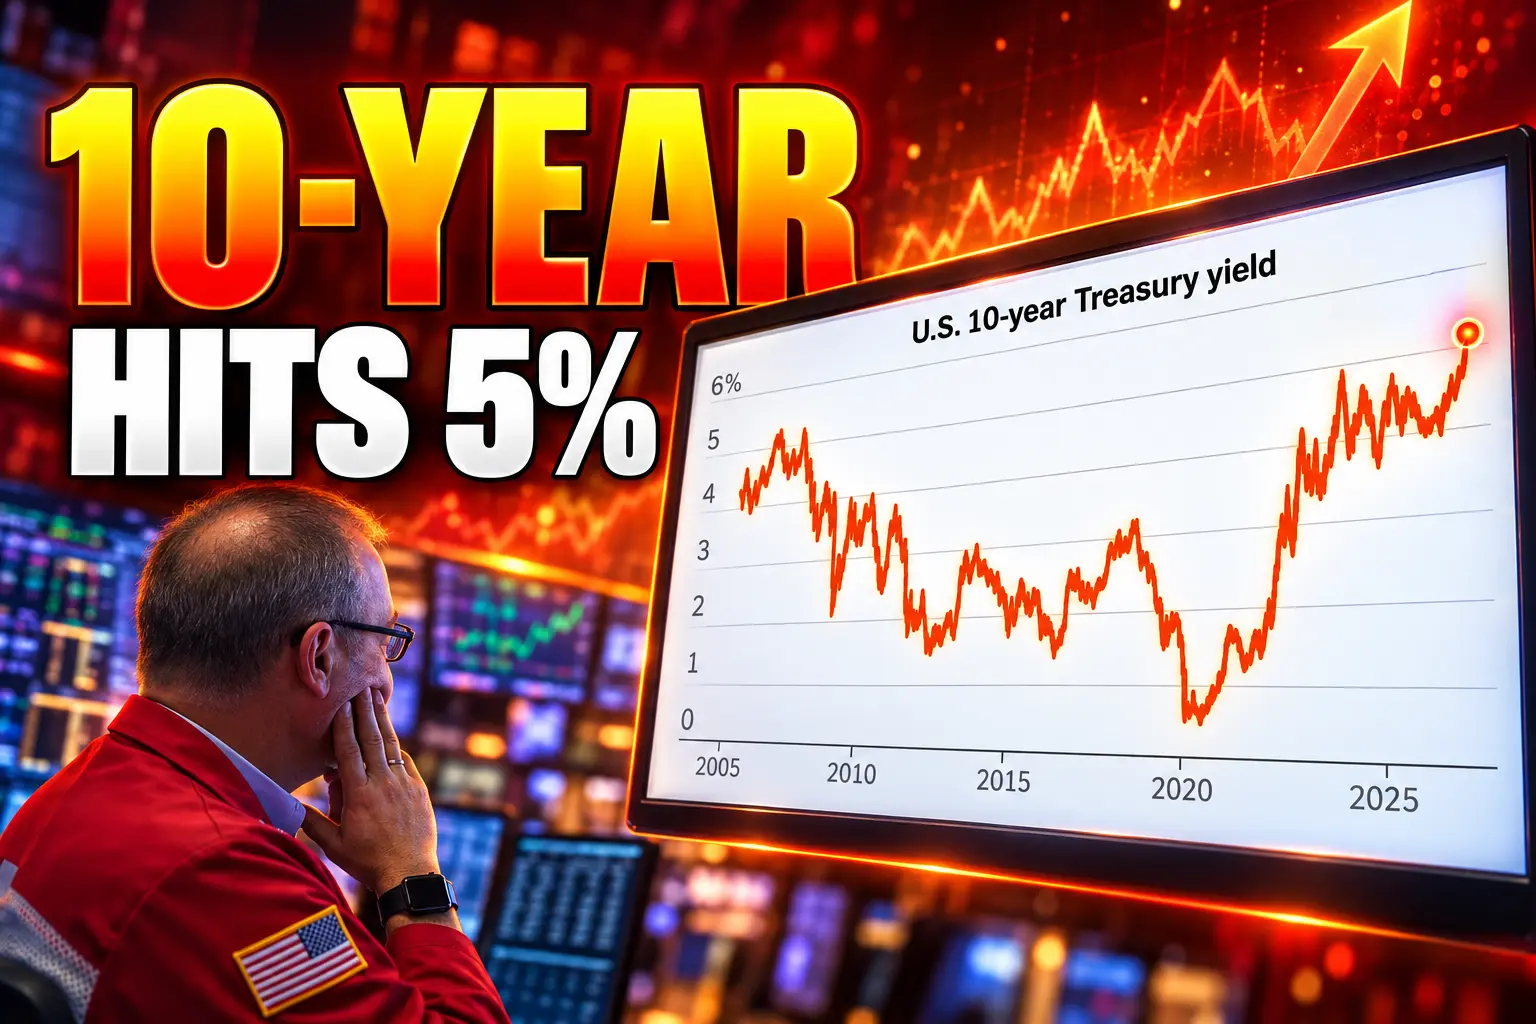
The 10-year Treasury yield’s 5% break taxes AI stocks as capex and a $40 trillion debt load compete for capital.

The 10-year Treasury yield reached 5.029% by 5 a.m. ET on Tuesday, September 15, its highest level since 2007. It had already tagged a session high of 5.041%, and U.S. stock futures pointed to a lower open after a losing Monday.
The Federal Reserve’s two-day meeting started the same morning, with a rate decision due at 2 p.m. ET on Wednesday. The bond market did not wait for the statement. Global yields rose with Treasurys, including Japan’s 10-year at 3.025%, a 30-year high.
The 10-Year Note Clears 5% Before the Fed Votes
Overnight, the benchmark added 7 basis points to 5.029%. The 20-year yield was at 5.434% and the 30-year at 5.391%. The 2-year, which tracks policy odds more tightly, was at 4.663%.
Those are trading prints. Monday’s official 10-year close of 4.97% still sat a hair under the round number, with the 20-year at 5.37% and the 30-year at 5.34%. Monday’s intraday high of 5.014% was the first poke above 5% since October 2023. Tuesday’s 5.041% high cleared that old tag.
TREASURY YIELDS AROUND THE 5% BREAK
| Maturity | Sept. 14 close | Sept. 15, 5 a.m. ET |
|---|---|---|
| 2-year | 4.65% | 4.663% |
| 10-year | 4.97% | 5.029% |
| 20-year | 5.37% | 5.434% |
| 30-year | 5.34% | 5.391% |
On January 2 the 10-year closed at 4.19%. The climb to 5.029% is 0.839 percentage point in a little over eight months. Bond prices move the other way, so that rerating has already marked down existing notes and, by extension, every loan that prices off them.
Futures Price a First Hike Since 2023
Chairman Kevin Warsh, in the job since May, is running his first full policy meeting as the 10-year sits above 5%. The funds rate is 3.50% to 3.75%. A quarter-point move would take it to 3.75% to 4.00%, the first increase since July 2023.
WHAT FUTURES PRICE FOR WEDNESDAY
- The odds: CME FedWatch put the implied odds of a quarter-point hike at 92.3% on Tuesday, up from 87.3% on Monday.
- The clock: The statement and new projections are due at 2 p.m. ET on Wednesday, September 16.
- The gap: Policy is still well below a 5% 10-year, so the long end is not waiting on the front end.
On August 28 at Jackson Hole, Warsh said inflation had been above target for 65 months and that summer readings had not convinced him the trend had “meaningfully improved.” The 12-month PCE rate was 3.7% and the six-month pace 4.1%. He set a test, not a path.
Here is my standard: We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.
Kevin Warsh, Federal Reserve chairman, Jackson Hole, August 28, 2026
Carol Schleif, chief market strategist at BMO Wealth Management, said in an email on Tuesday that the Fed has “little choice but to hike rates” this week, because the bond market has been “signaling for weeks that higher rates are warranted.” She added that stocks would be disappointed if the committee did not move.
AI Capex Is Bidding Against the Treasury
The usual story is that a 5% 10-year is gravity on stock prices. A 5% coupon is a 20-times-earnings claim on a payment that never grows, so cash and bonds start to compete with equities again after years when they did not. That math is real. It is also incomplete.
Warsh spent the first third of the same speech describing a capital scramble that would have sounded strange in the saving-glut years. Annualized token sales at the two leading AI labs, he said, were more than $100 billion, up 500-plus percent from a year earlier. Equipment and intangibles investment was running at about 9% on a four-quarter basis, the fastest since 2021, and he said more than half of this year’s cap-ex growth can likely be tied to the AI buildout.
Ever-expanding pools of capital are pouring into AI-related infrastructure of all sorts.
Kevin Warsh, Federal Reserve chairman, Jackson Hole, August 28, 2026
S&P 500 profits, he said, had grown by more than 20% over the past year, and credit spreads sat near the low end of their historical range. He would be “hard pressed to describe broad financial conditions as restrictive.” Housing and agriculture, he noted in the next breath, were already showing strains.
That split is the bind. The companies funding data centers out of double-digit margins can live with a higher coupon. The rest of the market funds itself in the same pool. Chip and AI names were already sliding as the 10-year crossed 5%, with oil doing as much damage as any lab-safety headline. Brent was at $107.37 and West Texas Intermediate at $103.24 after attacks on Saudi export routes, including a pipeline that can move as much as 4% of global supply.
Interest on the Debt Is Already $931 Billion
Washington is in that pool too. Gross national debt crossed $40 trillion in August. The Congressional Budget Office’s monthly review, cited by the Committee for a Responsible Federal Budget, showed the government had $2.0 trillion borrowed in 11 months of fiscal 2026, including $168 billion in August.
Interest is the piece that moves with the 10-year. The Peterson Foundation’s tracker, built from Treasury budget data through July, put year-to-date debt service at $931 billion in interest through July, up 10.6% from $842 billion in the same stretch of fiscal 2025. That made interest the third-largest federal outlay after Social Security and Medicare.
THE INTEREST TAB BEHIND THE 5% 10-YEAR
- Through July: $931 billion in fiscal 2026, versus $842 billion a year earlier.
- Last full year: $970 billion in 2025, roughly double the $476 billion record in 2022.
- CBO path: $1.0 trillion of net interest in 2026, $2.1 trillion in 2036, and $16.2 trillion over the next decade.
- Share of the economy: 3.2% of GDP in 2026, above the 1991 high, and 18.5% of federal revenues by the end of 2025.
Florian Spaete, senior bond strategist at Generali Investments, said the break above 5% “signals that markets are demanding a higher term premium for persistent inflation, fiscal risks, heavy issuance and rising capital demand, rather than treating the sell-off as a temporary overshoot.” Heavy issuance is not a mood. It is the refunding calendar for a $40 trillion borrower.
October 2023 Gave Way Within Weeks
A 5% 10-year is rare in this century, which is why desks treat it as a line. It is not a law. What happened after the last two prints is the better guide, and they do not agree with each other.
THE THREE TRIPS TO 5% ON THE 10-YEAR
- July 2007: The last time yields held above 5% for more than a moment. The financial crisis followed, and the 10-year spent most of the next 16 years well below that line.
- October 23, 2023: The yield reached 5.02%, then fell back toward 3.8% by year-end as the Fed’s tone softened. The S&P 500’s drawdown around that move was about 10%.
- September 14-15, 2026: Monday tagged 5.014% and Tuesday printed 5.029%, with a 5.041% high, as oil, issuance, and a priced hike arrived together.
David Kostin, Goldman Sachs’s chief U.S. equity strategist, wrote last year that equities typically rise with bond yields when the market is lifting growth forecasts and struggle when the driver is fiscal concern. Both drivers are on the tape this week. Warsh’s own numbers show cap-ex and profits running hot. The CBO and Peterson figures show a borrower that cannot step aside.
Stocks have risen through much higher yields when growth was strong, as in the late 1990s. They have also used 5% as an exit when the story was supply and inflation, as in October 2023. The open argument is which tape this is.
Who Gets Hurt If Yields Stay Above 5%?
Barclays strategists, in a Tuesday note, said earnings have so far offset the drag from higher rates, but that the 5% line is where that offset has historically gotten harder to keep.
While earnings have so far offset the drag, the approaching 5% threshold in 10Y yields marks a historically important inflection point, beyond which rates have typically become a more persistent headwind for equities.
Barclays strategists, note, September 15, 2026
WHERE STRATEGISTS SPLIT
- BlackRock: The BlackRock Investment Institute said higher global rates raise the hurdle for equity returns but “have not knocked us off our pro-risk stance,” and it is keeping U.S. equity and AI overweights because earnings can offset a higher cost of capital when yields reflect stronger investment.
- Barclays: Constructive on earnings, with a warning that the cushion gets harder to hold if yields move “materially above current levels.”
- BMO: Schleif said firms borrowing for AI “can handle the recent uptick in borrowing costs relative to their strong double-digit margins,” and that rising yields are “unlikely to slow down corporate America’s AI, infrastructure and reshoring spending.” She still expects “a more meaningful pullback of 10%” through the fall, citing oil, yields, midterm-election uncertainty, and stocks sitting only slightly off all-time highs.
Private domestic final purchases, Warsh said, have risen at a pace of nearly 3% so far this calendar year, and the jobless rate is 4.1%. Those are not recession prints. They also do not set the multiple. The multiple is set in the bond market, and the bond market is asking for 5% on the benchmark note while housing already feels the same bid.
The Long End Has Already Done the Tightening
A Wednesday hike, if it comes, will be the headline. Most of the work on long-term borrowing costs is already in the price. Policy at 3.75% to 4.00% would still sit below a 5.029% 10-year and a 5.391% 30-year. The term premium Spaete described, the refunding behind $931 billion of interest, and the AI buildout Warsh called a hinge are not items the statement can reverse in an afternoon.
Bank of Japan policymakers are expected to lift their rate by 25 basis points to 1.25% on September 18, another bid for scarce duration. Schleif’s 10% pullback is a forecast, not a print. The print is the 10-year above 5% going into a Fed meeting that futures have already called.
If Warsh delivers the hike and then tries to keep the rest of the path unsaid, as he argued at Jackson Hole he would, the next move in stocks will still run through the same 10-year. That is the rate the AI boom, the Treasury, and a $100 oil market are all paying now.
Disclaimer: This article is news reporting and market analysis for information only. It is not investment advice, a recommendation to buy or sell any Treasury, stock, fund, or other security, or a forecast you should trade on. Speak with a licensed financial adviser or investment professional who knows your accounts, time horizon, and risk limits before you change a portfolio. Yields, Fed odds, oil prices, and fiscal totals in this piece match the sources dated around September 15, 2026, and those figures can move in the next session.

Senate Advances a College Sports Bill Athletes Did Not Write

Tarantino Hands Off Cliff Booth, Then Novelizes Him Anyway

AcademyAI Raises £1.65 Million to Score Staff AI Skills

Vinicius and Mbappe Hid the Ceuta Shirt Madrid Posted

Google Inherits Samsung Gallery Backup as OneDrive Exits

Musk to Dell: How AI Split the World’s 10 Richest in 2026

Microsoft’s 95.95% Cyber AI Score Skips Its Own Leaderboard

Free Live Sports Streaming in 2026: What to Watch Without Cable

G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning

Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 NEWS4 months ago
Musk to Dell: How AI Split the World’s 10 Richest in 2026
-
 NEWS2 months ago
Microsoft’s 95.95% Cyber AI Score Skips Its Own Leaderboard
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-
 NEWS3 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning
-
 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 BUSINESS2 years ago
Retail Banking vs Commercial Banking: A Comprehensive Guide
-

 ENTERTAINMENT2 years ago
Andrew Garfield’s Amazing Spider-Man Movies Now Streaming for Free
-

 NEWS4 weeks ago
The Yankees Bet Aaron Judge Can Skip the Minors