BUSINESS
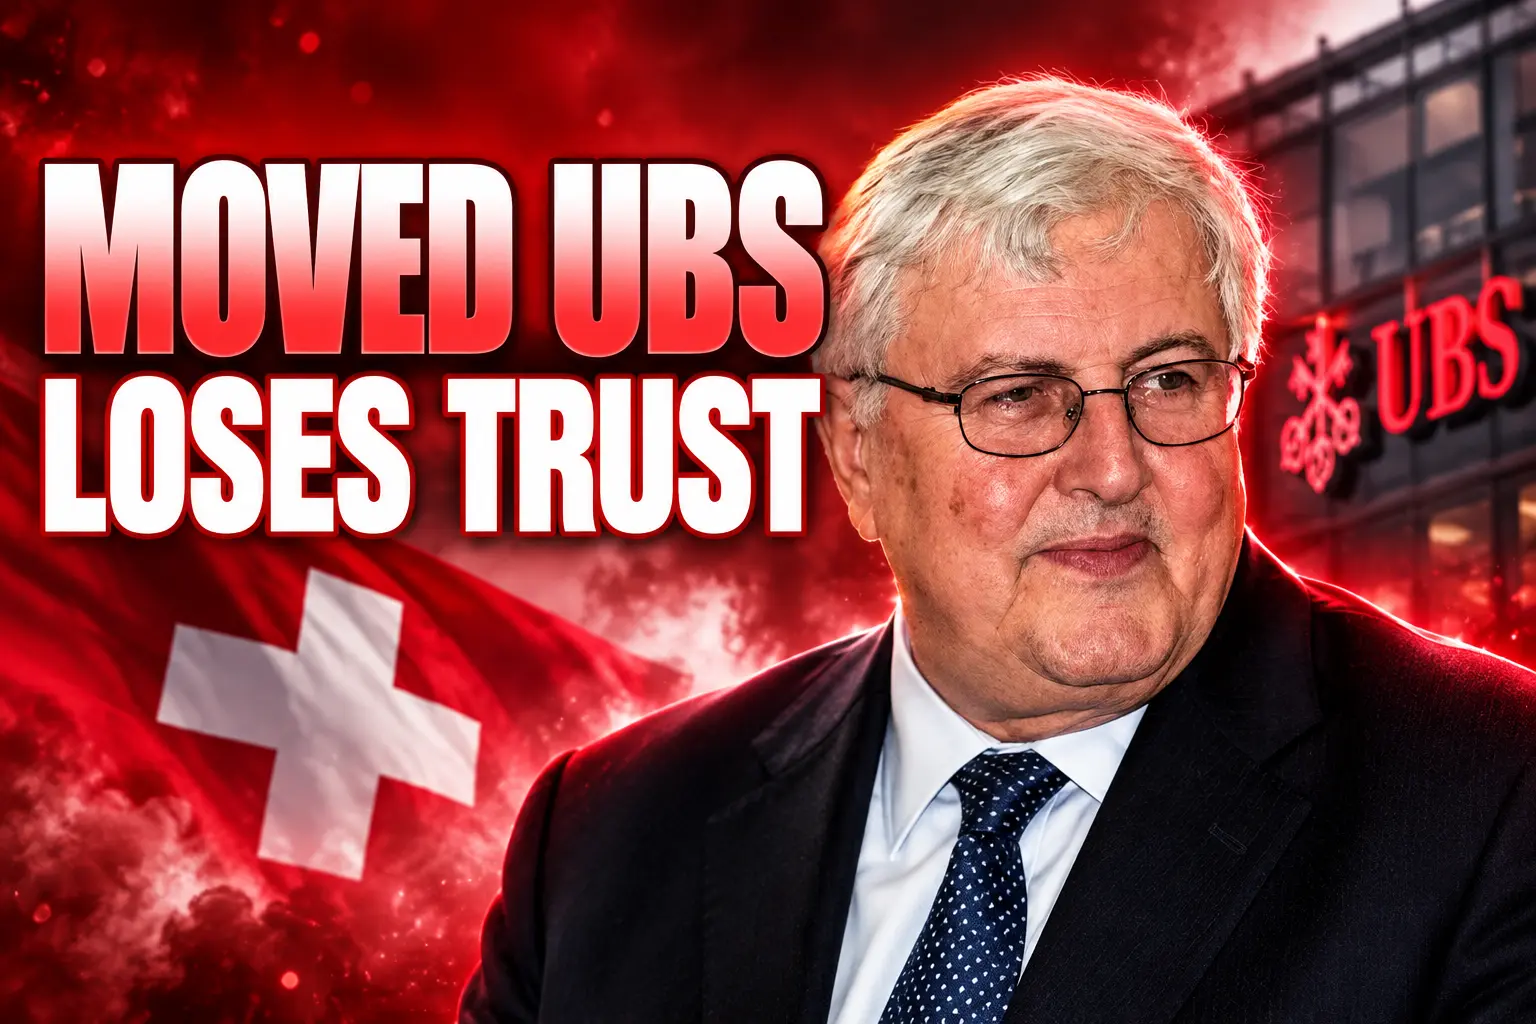
Rudi Bogni Says a Moved UBS Would Lose Swiss Trust
A 2025 warning from UBS’s former private-bank chief now sits on a live capital fight: Swiss trust is the franchise, and Singapore already books the clients.

Rodolfo “Rudi” Bogni said in March 2025 that UBS would not be the same bank in Singapore, London or New York. He said the private bank’s image is bound up with the trust Switzerland still enjoys as a country.
That line sat on the shelf while Zurich argued about capital. Late September 2026, when the Council of States voted to make UBS back foreign units with 90% CET1, it became the second invoice on a headquarters fight the first invoice cannot price.
The Unused Answer From the Athenaeum
The interview was on 26 March 2025, in the Drawing Room of London’s Athenaeum Club, where Bogni has been a member for nearly three decades. He is 77, Italian-born, and splits his time between London and Bottmingen, near Basel. Later that day he was due at a Bitcoin event in the same building.
From 1997 to 2000 he ran Swiss Bank Corporation’s, then UBS’s, global private bank, after taking the loss-making London office of Bankverein in 1990. He is not a bystander to the brand he is describing.
The bank’s image is inseparably intertwined with the trust Switzerland enjoys as a country. UBS, especially its private bank, would not be the same if based in London, Singapore or New York.
Rudi Bogni, former head of UBS global private banking, Athenaeum Club, March 2025
He called a move hard to imagine. Secrecy, he said, was never the foundation. Trust was. When banks chase volume at the client’s expense, they leave the Swiss model, which he still casts as advice rather than brokerage.
Extra Capital Is Only the First Invoice
The live argument in Bern is not about marble and letterhead. It is about how much hard equity the parent must hold against businesses that sit outside Switzerland, after UBS absorbed Credit Suisse and became the country’s only global bank.
On 6 June 2025, after the Federal Council published its package, UBS said the full deduction of foreign subsidiaries, plus other hits, would mean around $24 billion of extra CET1 at UBS AG on a first-quarter 2025 pro-forma, against a target CET1 ratio between 12.5% and 13%. The bank called the jump extreme and out of line with other centres.
In late September 2026 the Council of States backed a 90% CET1 rule for foreign units and rejected a cheaper 50/50 mix of CET1 and AT1 that the bank had wanted. Finance Minister Karin Keller-Sutter said on 26 September 2026 that UBS was unlikely to leave, and that a move would cost more than the new rules and be legally messy. Chairman Colm Kelleher, speaking earlier that month at the Swiss Bankers Association meeting in St Gallen, said the aim was to stay, then added that if the bank were no longer competitive it would have to think about it.
CAPITAL PACKAGES ON THE TABLE
| Package | Date | What it asks |
|---|---|---|
| Federal Council full deductions | 6 June 2025 | UBS: around $24 billion extra CET1 at UBS AG |
| Council of States foreign-unit rule | Late September 2026 | 90% CET1 against foreign units; 50/50 CET1/AT1 rejected |
Shareholders have started to treat the head office as a capital-structure choice, not a patriotic one. Artisan Partners, on 30 September 2026, urged the bank to leave, calling the stricter rules a grim reality against US rivals. Sergio Ermotti, the chief executive, had taken the other side on 20 November 2025 at a JPMorgan European financials conference, saying, “We never, ever threatened to leave the country. This is absurd.” He said a Swiss UBS was the best outcome, and that he and Kelleher were working on that.
Those two sentences can both be true in the same year. The threat is useful in Bern. Following through is a different trade, and Bogni’s point is the part of that trade that does not appear in CET1.
THREE WAYS A MOVE COULD BE DONE
- Shift the holding company: Shareholder approval, a new home supervisor, and a heavy tax bill.
- Merge with a foreign bank: The Swiss units become foreign-controlled and still need the Swiss supervisor’s extra nod.
- Be bought: The shorter path on paper, and the one merger gossip in late September 2026 kept circling, with no deal on the table.
A brass plate in Singapore would not dodge that plumbing. Neither would one in New York.
Why He Says Booking Centres Cost Him the Job
The irony in Bogni’s warning is that he already moved the work. In the 2025 conversation he said he had pushed, while at UBS, to create booking centres around the world so the bank could serve tax-compliant clients. “It was probably too early, maybe it even cost me my job.”
He had said the same thing in public a decade earlier. In a 2015 essay he wrote that in 1997, when he came to Switzerland to run SBC’s private bank and then the merged UBS franchise, he had argued for domestic booking centres in other key countries, with better-trained bankers and a tighter link to “society’s better values.” The article, he wrote, was not well received. He did it anyway.
Two of the things he still names with pride from that period are a graduate training programme for wealth managers and, with then-chairman Marcel Ospel, the Optimus Foundation. The days of banking secrecy, he wrote in 2015, were already numbered. He still thought the deeper fight was state control of the citizen, with tax as one tool among others, and he still wanted clients to pay what they owed.
By 2025 the tax map had moved again. Compliant clients, he said, can now be served from Switzerland itself. The booking centres were a way to keep the Swiss model honest in a world that no longer tolerated hidden money. They were not, in his telling, a rehearsal for taking the group home to Singapore.
BOGNI’S PATH INTO THE ARGUMENT
- Early 1970s: Starts at Chase Manhattan, then becomes treasurer of Midland Bank.
- 1990: Takes SBC’s loss-making London office, later UBS in the UK.
- 1994: SBC buys Warburg while Marcel Ospel is pulling the group into derivatives through Chicago’s O’Connor.
- 1997 to 2000: Runs the global private bank and pushes overseas booking centres.
- End of 2024: Steps off the Liechtenstein princely foundations, after more than twenty years on the boards of Kedge and Waypoint for the Bertarelli family, and after sitting on LGT’s board.
- 26 March 2025: Tells an interviewer the group would not be the same if based in London, Singapore or New York.
- 6 June 2025: UBS publishes its around $24 billion CET1 estimate on the Federal Council package.
- Late September 2026: The Council of States backs 90% CET1 on foreign units.
He described the 1990s London shop as pirates more than gnomes, doing M&A on contracts for difference and watching the Warburg purchase land as a surrender by the old British elite. That is the man now saying the franchise dies if the nameplate leaves Zurich.
Hong Kong’s $2.9 Trillion Cross-Border Book
Bogni’s 2025 worry that Swiss private banking had lost global share now has a clean scoreboard. Boston Consulting Group’s Global Wealth Report 2026 found that Hong Kong booked $2.9 trillion of cross-border wealth in 2025, up 10.7%, and overtook Switzerland for the first time. Global financial wealth rose 10.7% to $333 trillion. Cross-border wealth rose 8.4% to $15.7 trillion, with the top ten centres taking almost 90% of new offshore flows.
BCG’s authors split the map into two networks. One is anchored by Hong Kong and Singapore and serves mainland Chinese, Indian and Southeast Asian capital. The other is anchored by Switzerland, the United States and the United Kingdom and serves European, Middle Eastern and Latin American wealth. Michael Kahlich, a BCG managing director and co-author, said client proximity is what matters.
TWO WEALTH NETWORKS IN BCG’S 2026 MAP
| Network | Anchors | Who it serves |
|---|---|---|
| Asian | Hong Kong and Singapore | Mainland Chinese, Indian and Southeast Asian capital |
| Western | Switzerland, the US and the UK | European, Middle Eastern and Latin American wealth |
The Swiss domestic industry is not empty. KPMG’s 2026 study of 68 private banks found a record CHF 3.5 trillion of assets under management at the end of 2025 and CHF 96.0 billion of net new money. Large banks in the sample took CHF 66.6 billion of that new money, 52.7% more than in 2024. Medium banks held CHF 23.3 billion, 5.0% lower. Small banks took CHF 6.2 billion, 61.4% higher. The licensed private-bank count fell from 156 in 2010 to 79 by the end of May 2026. The median cost-income ratio sat at 78.2%.
Those inflows are the safe-haven bid Bogni is talking about. They are also compatible with Hong Kong taking the cross-border crown. Different books, different clients, same pressure on a small country that still wants to be the Western node.
The Next Billionaires Do Not Need Bank Secrecy
Asked whether Switzerland can still sit in the right place for new wealth, Bogni went straight to geography. Most new money, he said, is being created in the United States and Asia. Europe is stagnating, “particularly in technology, what used to be 30 percent of market cap is now under 10.” Switzerland, he said, must remain relevant to those new wealth creators, culturally and geographically.
Elon Musk, he thought, is too US-centric to be pulled. The next generation is a different bet. Children of US and Asian billionaires, in his view, are less interested in empire-building and more open. They might take the Swiss proposal. The proposal, as he frames it, is not a numbered account. It is a place that still looks like a country with cohesion.
He split Switzerland into two economies that have to live in one polity: SMEs tied to the eurozone inside a 400-kilometer radius of the border, and finance and pharma tied to the dollar. That split, he said, is a political tension. The cohesion that lets Switzerland punch above its population was built over centuries and is not guaranteed. Petty fights over CEO pay, he said, do not help.
If the next family office is in Singapore because that is where the operating companies are, Bogni’s “Swiss proposal” has to travel without the old secrecy premium. He thinks it can, from Switzerland. He does not think it survives a group headquarters that has left.
Gold in His Pocket, Bitcoin on LGT’s Menu
The Bitcoin event at the Athenaeum was not a conversion. Asked if he still preferred gold in his pocket, Bogni said, “Absolutely.” He wants central bank digital currencies as plumbing. He does not want crypto. “If I already have trouble trusting state currencies, how should I trust something metaphysical? Bits and no bits? It’s not for me.”
He will grant other people the right to speculate. He will not join them. Surveillance in a CBDC is, he said, a real risk in a state like China, though he thinks it will be rules-based and algorithmic rather than a clerk reading every payment. In the UK he already feels the intrusion. Ask for 4,000 pounds in cash, he said, and the bank interrogates you. Sometimes he asks for cash “just to annoy them,” and when they ask what for, he answers, “So you don’t know how I’ll spend it.”
The punchline sits on his own CV. He left the Liechtenstein princely foundations at the end of 2024 and had served on the board of LGT, the princely family’s bank. LGT had already begun offering direct Bitcoin and Ether holdings to certain professional clients in 2022. The house he helped oversee sells the asset he will not touch. That does not make him a hypocrite so much as a marker of how far the industry has moved while he has stayed with gold.
His longer gloom is demographic. If birth rates keep falling, he said, Europe could lose half its population in a generation, with China on the same path, while politics looks only 12 months ahead. Pensions and health care still have to be paid from a shrinking base. “So, yes, I am a bit pessimistic. Well, you’re not really pessimistic, otherwise you stop living.”
New York, Not Singapore, Is the Live File
Singapore is the city in Bogni’s sentence because it is the Asian private-banking rival everyone in Zurich can picture. The file that actually opened in 2025 was American. On 9 December 2025, Senator Elizabeth Warren, ranking member of the Senate Banking Committee, wrote to Kelleher about reported talks with Treasury Secretary Scott Bessent on moving the headquarters to the United States if Swiss capital rules did not ease.
Warren’s letter put the Credit Suisse rescue in hard numbers: UBS went from about $1 trillion in assets to nearly $1.7 trillion, a jump of more than 50%, and the Financial Stability Board moved it up a systemic-risk tier. She wanted to know whether Kelleher had discussed a US home with Trump administration officials, and whether anyone had promised lighter rules. The lessons Finma drew from Credit Suisse are the reason Bern is rewriting the capital code in the first place.
WHAT WE KNOW
- The Swiss vote: The Council of States backed 90% CET1 on foreign units in late September 2026.
- The bank’s June 2025 number: Around $24 billion extra CET1 at UBS AG under the Federal Council’s full-deduction design.
- The US channel: Warren’s 9 December 2025 letter treats Bessent talks as a matter for the Senate record.
- The brand argument: Bogni, March 2025, said the private bank would not be the same in London, Singapore or New York.
WHAT IS UNCONFIRMED
- A live bid: Reports of foreign banks sounding out a merger have not produced a named offer UBS has confirmed.
- A US welcome: Warren asked whether anyone promised lighter US rules. That answer is not public.
- A Singapore headquarters plan: Bogni named the city. The documented contingency talks have been about the United States.
Keller-Sutter can be right that leaving would cost more than complying, and Kelleher can still keep the option in his pocket for the next chamber of parliament. Artisan can be right about returns on extra equity. That does not answer Bogni. He is not pricing CET1. He is pricing what clients think they are buying when the letterhead still says Switzerland.
He already built the overseas booking centres. He says that may have cost him the job. The group home, in his account, is the one thing that cannot follow them to Singapore without turning UBS into a different private bank. The capital vote has made that a current sentence, not a club-room recollection.

Saquon Barkley’s Hamstring Leaves the Eagles Thin in London

The Online US Passport Still Needs a Witnessed Oath

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-

 NEWS4 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning