BUSINESS
Higala’s $4 Million Bet Still Has Eight Rural Banks
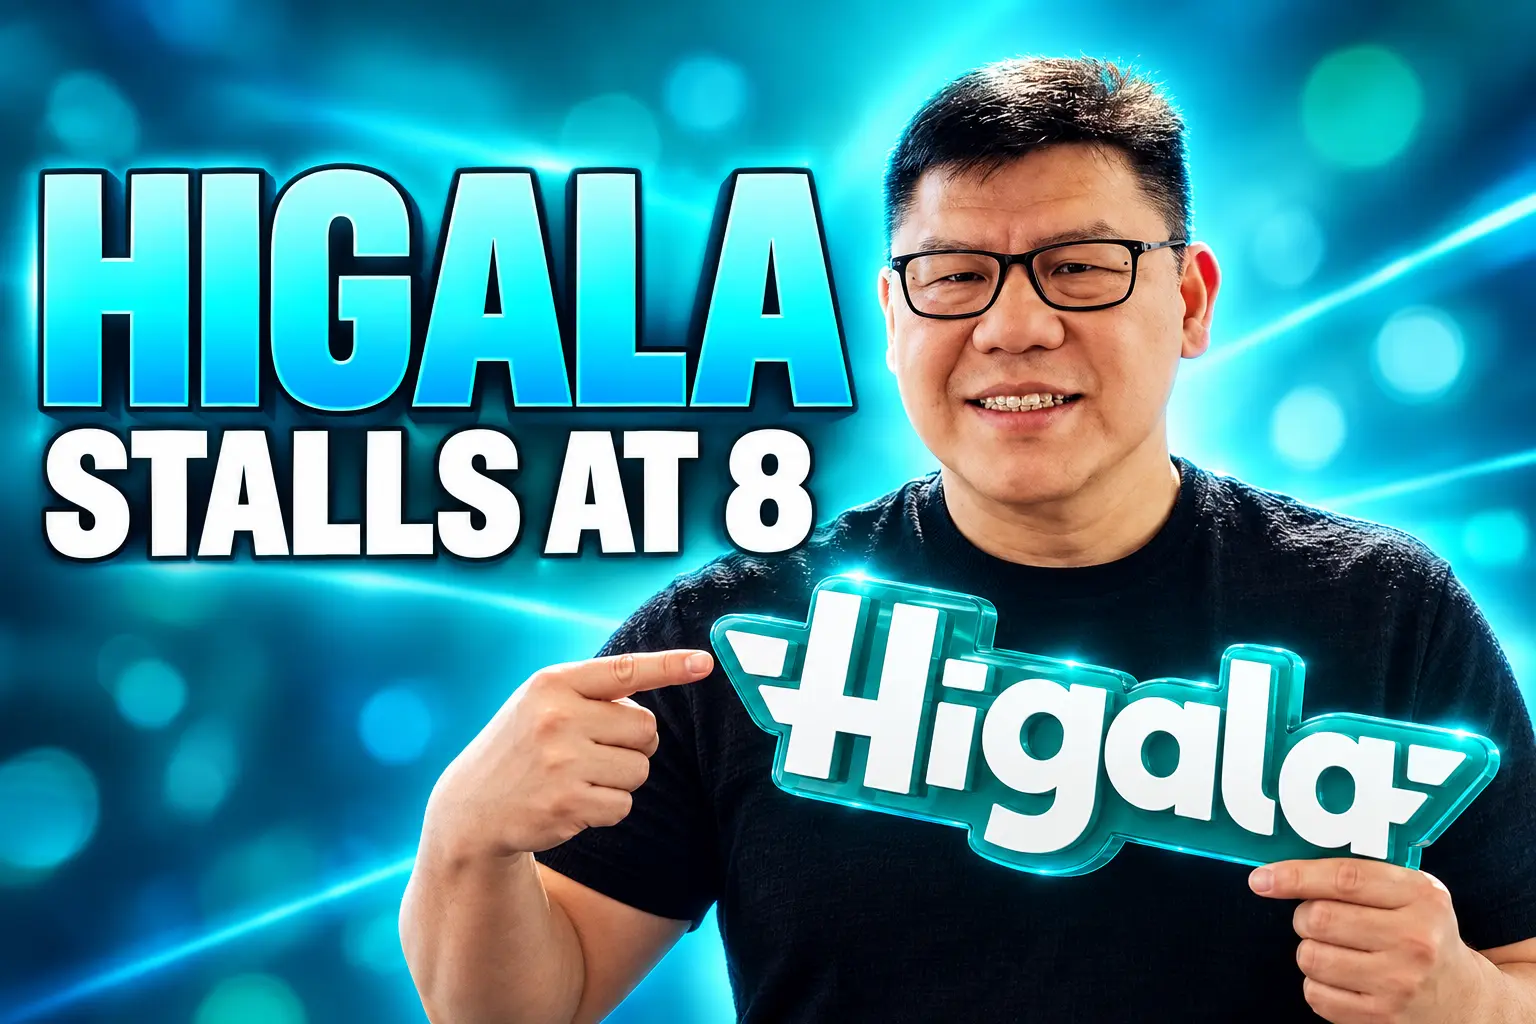
Higala closed a $4 million seed and put eight rural banks on SynerFi, far short of the 40-bank Phase 1 it pitched after the $2.8 million extension.

Higala has eight rural banks live on SynerFi and a seed round that stopped at $4 million. That is the scorecard on a pitch that once put 40 banks at launch and a much larger round right after.
Chief executive Winston Damarillo sold the March 18, 2025 raise as the cash that would open instant digital payments to rural lenders that could not build their own stack. Rizal Commercial Banking Corp. would hold the license. Higala would hold the software. The first eight names went public on July 2, 2025. No later named roster has followed.
The $2.8 Million Pitch and the 40-Bank Promise
Higala, a Makati instant-payment firm founded in 2023, extended its seed round to $2.8 million on March 18, 2025. Singapore’s 1982 Ventures led. Talino Venture Studios, which Damarillo also runs, stayed in. Chemonics International was already on the cap table from the 2024 start.
The money was meant to fund a platform-banking launch in the second quarter, later pinned to mid-July, so rural banks, thrift banks and other small lenders could offer digital payments and join instant rails. Damarillo told the briefing he wanted 60 percent of the market by year-end, and he put a follow-on round of $10 million to $15 million on the calendar after that launch.
Scott Krivokopich, managing partner at 1982 Ventures, tied the check to a national volume claim, saying the team would make the country’s five billion monthly transactions faster, cheaper, and available to all sectors of the economy. Vice Catudio, Higala’s president and chief revenue officer, said the network was built on ISO 20022-native plumbing.
The March list mixed two things that later got separated. One was “initial 40 participants” in RCBC’s SynerFi service. The other was a string of ATMGo rural banks, among them Rizal Microbank, Guagua Rural Bank, SNR Rural Bank, Rural Bank of Cadiz, Marayo Bank, Pangasinan Bank and Rural Bank of Silay. That list, which put 40 rural banks named for Higala’s network beside the ATMGo partners, was a pipeline. It was not a live InstaPay switch.
Eight Banks Went Live in July
On July 2, 2025, in Taguig, Damarillo and RCBC executive vice president Lito Villanueva, who is also chief innovation and inclusion officer, named the first live cohort. Eight rural banks, they said, were on SynerFi and headed onto InstaPay in a few weeks. Damarillo called it the start of giving the small-bank sector tools that had sat with universal banks.
THE FIRST LIVE SYNFRFI COHORT
| Bank | Base named at the briefing |
|---|---|
| Rural Bank of San Antonio | Southern Luzon |
| Rural Bank of Lipa City | Batangas |
| Progressive Rural Bank | Laguna and Batangas |
| Banco Abucay | Bataan |
| Rural Bank of Hermosa | Bataan |
| Money Mall Rural Bank | Compostela Valley |
| First Philippine Partners Bank | Cebu |
| Lagawe Highlands Rural Bank | Ifugao |
Villanueva said the partners were targeting 40 rural banks in Phase 1, with eight already in the room, and a wider Phase 2 after that. Damarillo said 12 more would join within the year, which would have taken the 2025 plan to 20. RCBC’s own aim, stated the same week, was to lift rural-bank InstaPay use from 5 percent of 358 rural banks, about 18 names, to 20 percent within two years.
Ronaldo Recto, president of Rural Bank of San Antonio, described the offer as a way to skip a tech hire he could not staff.
Launching these services with zero capital intensity and without the heavy burden of building dedicated in-house tech and compliance teams is invaluable, enabling us to offer customers top-tier technology and services, truly digitizing our reach.
Ronaldo Recto, president, Rural Bank of San Antonio
Damarillo said the hard work had been the first build, two to three months with RCBC, and that a new tenant bank could be onboarded in two to three weeks once that base existed. If that clock had held, Phase 1 would have been a calendar problem, not an engineering one. The named list did not grow in public after those eight.
The Seed Hit $4 Million Without a Scale Round
The July briefing did one other thing. It expanded the round to $4 million, an extra $1.2 million, instead of opening the $10 million to $15 million scale round Damarillo had sketched in March. Talino, Chemonics, Kadan Capital, Tenco Capital and 1982 Ventures were named on the close.
Jamey Butcher, Higala’s chairman and chief executive of Chemonics International, said the extra money followed demand after the $2.8 million target was hit. He also said SynerFi would give rural-bank customers mobile banking for the first time, and he tied that to Chemonics’ almost 40 years of work in the Philippines and work in more than 160 countries. Higala restated the $4 million close on November 25, 2025, still listing the same eight banks.
THE MONEY AGAINST THE CALENDAR
- October 30, 2023: First seed money lands; Higala is a year-old Makati payments firm.
- March 18, 2025: Seed is extended to $2.8 million, led by 1982 Ventures, for a mid-year platform-bank launch.
- July 2, 2025: Eight rural banks are named live; the seed is lifted to $4 million.
- November 25, 2025: The $4 million close is announced again; the named rural-bank list is unchanged.
- September 28, 2026: Fundz still records a $4 million seed dated November 25, 2025, and no later round.
Tracxn, last refreshed on September 5, 2026, also keeps total funding at $4 million over four seed steps. The follow-on Damarillo had hung on a successful July launch has not appeared in those ledgers.
Why Rural Banks Still Sit off InstaPay
The national rails did not wait. Digital payments were 64.7 percent of retail volume in 2025, and the Bangko Sentral ng Pilipinas had already beaten its old 50 percent target. From January to August 2026, InstaPay and PESONet together moved P22.1 trillion, up 44 percent, across 5.8 billion transfers, up 142 percent. InstaPay alone, the real-time rail for amounts up to P50,000, ran about P11.1 trillion and 5.7 billion transfers in those eight months.
Rural banks remain a thin slice of that boom. Villanueva’s July 2025 figure was 5 percent of 358 rural banks on InstaPay. The central bank’s August 2026 physical-network table shows 345 rural banks by head office, plus 21 cooperative banks, or 366 rural and cooperative head offices in all. BancNet’s QR Ph person-to-person list as of August 31, 2026, names 10 rural banks on QR Ph as sender and receiver, out of 66 institutions on that sheet.
THE RURAL-BANK GAP ON THE RAILS
| Measure | Count | Date |
|---|---|---|
| Rural-bank head offices | 345 | August 2026, BSP |
| Rural and cooperative head offices | 366 | August 2026, BSP |
| Rural banks Villanueva said were on InstaPay | 5 percent of 358, about 18 | July 2025 |
| Named SynerFi rural banks | 8 | Last published November 2025 |
| QR Ph P2P rural banks, send and receive | 10 | August 31, 2026, BancNet |
The Rural Bankers Research and Development Foundation, citing BSP figures as of March 2026, said 251 of 370 rural banks held more than P50 million in capital, the floor for a head office and up to five branches. The next steps are P120 million for six to ten branches and P200 million beyond that, with a 2027 deadline. Capital is not the same as a payments switch. A small bank can meet the peso floor and still lack fraud monitoring, a core that speaks ISO 20022, and a sponsor for clearing and settlement.
RCBC Holds the License, Higala Holds the Stack
SynerFi’s split of labor is the product. Higala supplies the software. RCBC acts as the sponsor platform bank and handles compliance, clearing and settlement. The rural bank becomes a tenant. It keeps its name, its branches and its depositors, and it borrows a licensed rail it could not join on its own budget.
WHAT A TENANT BANK GETS
- White-label app: Each bank gets its own mobile app rather than sending customers to an RCBC brand.
- Digital onboarding: New depositors can open accounts without walking into a branch.
- CASA and InstaPay: Current and savings accounts sit behind real-time transfers once the sponsor path is live.
- Teller tools: A web application covers the branch counter so the physical shop stays open.
- QR and remittance: The July briefings also listed QR Ph in shops and inbound remittances as part of the suite.
The open-source layer under that stack is Mojaloop, the Gates Foundation-backed switch Higala has used since 2024, when it registered as an operator of a payment system. The Mojaloop Foundation framed the Philippine build as a superhighway for thrift banks, rural banks and microfinance firms.
News! Mojaloop-enabled Higala, the Philippines' first IIPS, will serve as a financial superhighway that will connect thrift banks, rural banks, and microfinance institutions so that everyone has access to financial services. More: https://t.co/gLN5J5GRAH#financialinclusion pic.twitter.com/uYbuDVwyTD
— Mojaloop Foundation (@mojaloop) April 29, 2024
Damarillo has compared the whole design to Brazil’s Pix plus Nubank: reuse the public rail, then rent a bank platform to whoever cannot afford a core of their own. In December 2025 he said the model had been proven in the Philippines and could be copied across Southeast Asia, with talks mentioned around Indonesia, Vietnam, Cambodia, Laos and parts of Latin America. The proof, on the public record, is still those eight names.
Circular 1240 Puts a Price on Looking Digital
The other change landed on September 21, 2026. Bangko Sentral Circular 1240, approved under Monetary Board Resolution No. 838 dated September 3, 2026 and signed by Governor Eli M. Remolona Jr., tells thrift, rural and cooperative banks that start to look like digital banks they may have to meet the same prudential bar as the country’s seven licensed digital banks, including a P1 billion capital requirement.
A flagged bank has six months from written notice. The circular also catches lenders that use digital platforms and post quarterly loan or deposit growth of more than 30 percent for two consecutive quarters. Supervisors can add reporting, freeze new digital products, and demand live fraud monitoring and automated anti-money-laundering tools. Acquisitions meant to turn a rural bank into a tech-led lender must show the P1 billion at application.
WHAT CAN TRIP THE RULE
- Digital-bank lookalike: The BSP decides the business model, or the capital and risk setup, no longer matches a countryside mandate.
- Fast digital growth: Loans or deposits rise more than 30 percent in a quarter, twice in a row, on digital channels.
- Conversion or buyout: A deal that turns the bank into a tech-led lender must clear the P1 billion floor on day one.
SynerFi’s pitch is digital onboarding, a mobile app and instant payments with no extra capital outlay. If that pitch works, deposits can jump. If deposits jump on a phone channel, Circular 1240 is the next letter in the mail. Most of the 370-bank rural sector is built around a P50 million floor, not a P1 billion one. The product that lowers the tech bill can raise the prudential bill.
Trackers Still List a $4 Million Seed
Fundz, updated September 28, 2026, still shows Higala’s last raise as a $4 million seed on November 25, 2025. Tracxn’s September 5, 2026 file says the same total. Neither records the $10 million to $15 million round that was supposed to follow a mid-year launch. Public posts about new rural-bank logos also stopped after the first eight, which is how a 40-bank 2025 target can expire without a correction.
The eight banks from San Antonio to Lagawe are a real on-ramp, and RCBC still has the license those tenants need. The original wager was larger: 40 banks in Phase 1, 60 percent of a market Damarillo did not define, and a scale round once the switch was hot. On the numbers that are in the open, that wager is still open, and Circular 1240 now sits on the path the product was built to walk.
Disclaimer: This article is news reporting on Higala’s funding, rural-bank onboarding and related Bangko Sentral rules. It is for information only and is not investment, banking, legal or financial advice. Readers who are considering a deposit, a shareholding, a partnership or a product decision should speak with a licensed banker, lawyer or investment adviser who can review their own facts. Funding totals, bank rosters and circular status follow the company notes, investor posts and BSP tables cited above and can change as new filings or notices appear.

Saquon Barkley’s Hamstring Leaves the Eagles Thin in London

The Online US Passport Still Needs a Witnessed Oath

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-

 NEWS4 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning