BUSINESS
Canada’s Big Banks Keep Tightening Their Grip on Mortgages
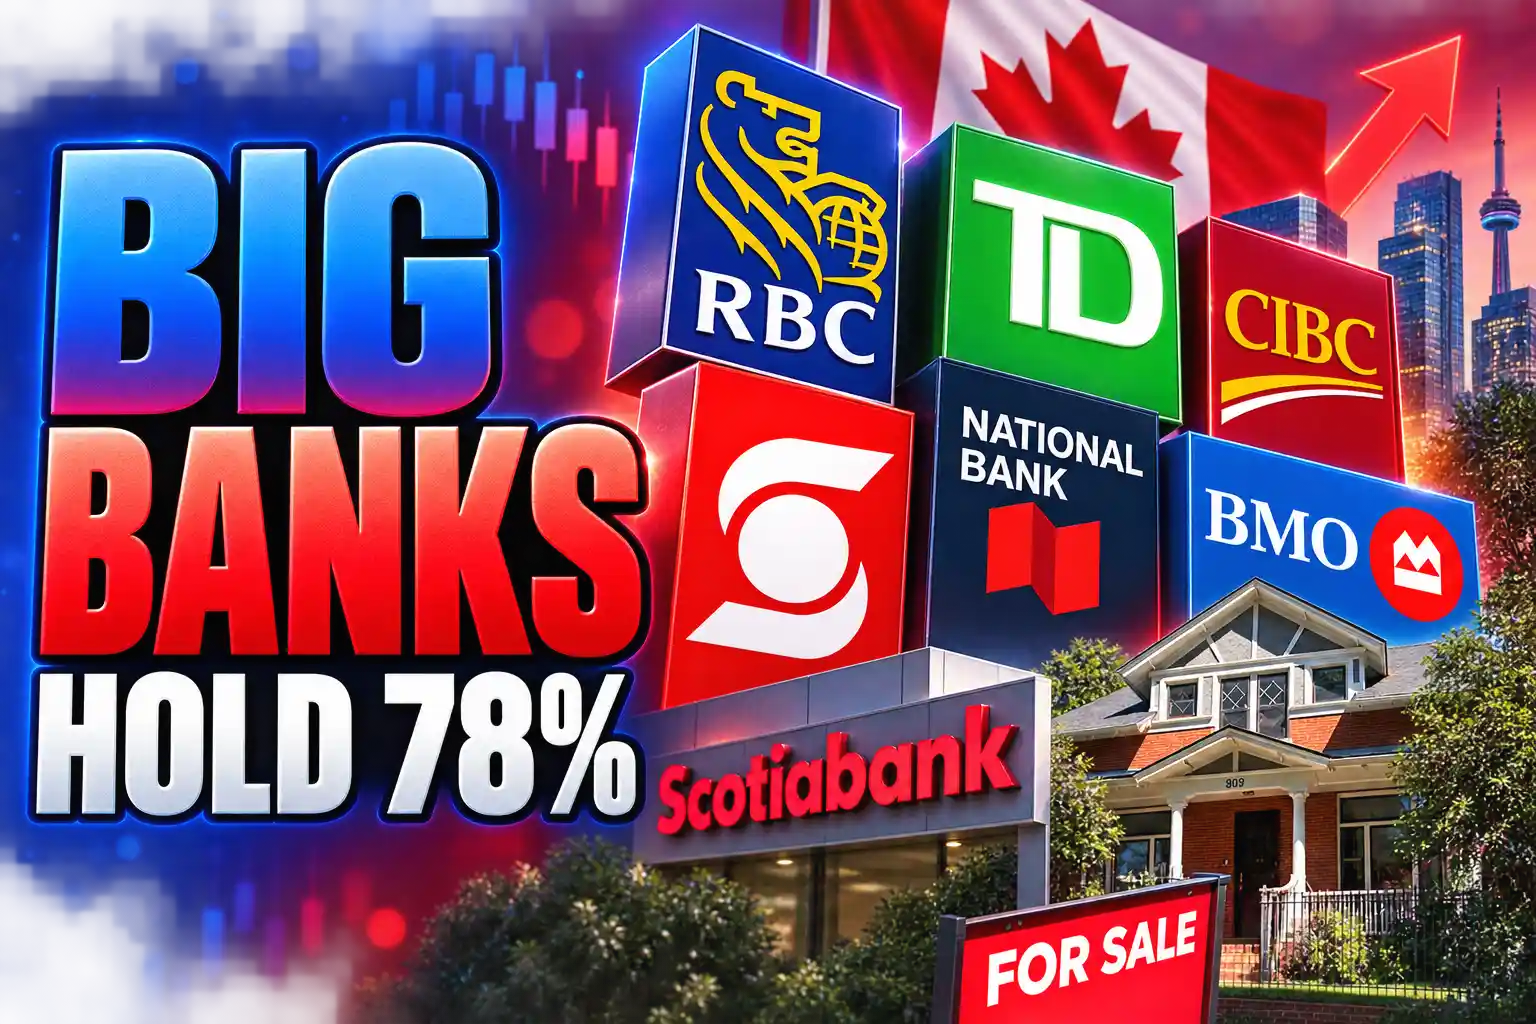
Canada’s Big Seven grew mortgage share to 78% even as brokers and monolines shopped cheaper rates, and the largest independent was taken private.

Canada’s Big Seven lenders held 78 percent of residential mortgages and home-equity lines in July 2025, up from 76.3 percent a decade earlier. The rate sheets got noisier. The names on the loans did not.
Hanif Bayat, CEO of the personal-finance platform WOWA.ca, mapped that split in 2025: mortgage finance companies originate a slice of new loans, then sell or securitize them, often to the same six banks whose branches the borrower never entered. Private equity later bought the largest of those independents. In June 2026 the federal regulator freed more capital for the six banks that already hold the book.
Canada’s $2.7-Trillion Mortgage Book Has a Familiar Owner
WOWA Data Labs put Canadian residential mortgage balances at about $2.7 trillion in the first quarter of 2026. Royal Bank of Canada still sat at the top of that pile with $495.8 billion. Toronto-Dominion held $418.4 billion, Scotiabank $338.0 billion, CIBC $292.8 billion, BMO $214.7 billion and National Bank $113.6 billion, a combined $1.873 trillion.
THE BOOK IN EARLY 2026
- RBC: $495.8 billion in Canadian real-estate loans, the largest single book.
- The six banks: $1.873 trillion combined, before Desjardins and the rest of the market.
- First National: $166.2 billion of mortgages under administration, mostly for investors, not as loans it keeps.
- MCAP: $155.5 billion under administration, with nesto at about $80.0 billion.
Those last three figures are servicing and administration, which is a different claim from owning the credit risk. Bayat noted in May 2025 that outstanding residential mortgage credit was about $2.07 trillion as of that January, plus more than $350 billion in home-equity lines, for $2.42 trillion of housing-secured lending. He also put the average bank return on the money they lend at about 1.5 percent, with residential mortgages among the lowest-risk books because of home collateral, default insurance and a long stretch of stable house prices.
Statistics Canada later put household credit market debt of $3,280.9 billion in the second quarter of 2026, with residential mortgages making up almost three-quarters of household debt. New mortgage borrowing in that quarter slowed to $19.4 billion, the weakest pace since the first quarter of 2024. The stock is huge. The flow has cooled. The owners of the stock barely changed.
Origination and Ownership Are Different Games
Market share looks like a fight over new loans. It is also a fight over who still holds the paper five years later. Bayat’s distinction is the one that survives a rate war: mortgage finance companies such as First National and MCAP together originate close to 10 percent of residential mortgages, yet they rarely keep those loans. They securitize them or sell them, often to RBC, TD, Scotiabank, BMO, CIBC and National Bank. The six banks’ ownership share is larger than their share of new files.
WOWA’s July 2025 read of the same channel put First National, MCAP and the Nesto group together at about 10 percent of residential loans under management. More than 85 percent of real-estate-secured lending is traditional mortgages; the rest is HELOCs. Banks fund those books with deposits. The independents fund with capital markets, NHA mortgage-backed securities and whole-loan sales. A borrower who takes a monoline quote can still end up, after the sale, as a bank’s customer on a servicer tape the bank never advertised.
That is why a cheaper five-year print from a broker desk does not show up, a decade later, as a smaller bank share. The shop is real. The transfer is quiet. Credit unions and smaller banks can undercut a posted branch rate and still lack the deposit base, the renewal machine and the brand that keep a file in-house when the term rolls.
From 76.3% to 78% in 10 Years
WOWA compiled lender reports and Statistics Canada figures into a July 2015 to July 2025 comparison. The Big Seven share rose to 78 percent from 76.3 percent. The leftover 22 percent is split among more than 20 smaller banks, hundreds of credit unions, mortgage finance companies, insurers, trusts and mortgage investment entities.
WHO GAINED THE HOUSING-CREDIT BOOK
| Lender | July 2015 share | July 2025 share |
|---|---|---|
| Big Seven combined | 76.30% | 78.00% |
| RBC | 17.40% | 18.80% |
| TD | 15.80% | 15.60% |
| Scotiabank | 13.50% | 12.60% |
| CIBC | 11.60% | 11.20% |
| BMO | 8.00% | 8.20% |
| Desjardins | 6.50% | 7.30% |
| National Bank | 3.50% | 4.20% |
RBC, Desjardins, National Bank and BMO took share. Scotiabank, CIBC and TD gave some up. The group as a whole still finished heavier. Bayat’s 2025 essay put the non-Big-Seven slice at 21.5 percent in January 2015 and 20 percent by 2025, a different cut of the same squeeze. Brand, branch networks and the habit of parking chequing, credit cards and the mortgage in one login all pull renewals back to the incumbent. Smaller lenders, he wrote, keep running into thin brand recognition and thin distribution even when they post a lower rate.
Hanif Bayat put the decade in one chart on X, and the punchline was the same as the table: the biggest lenders got fatter.
🇨🇦 Biggest lenders are getting fatter😉
📈 The Big Six + Desjardins grew their share of residential mortgages (+HELOCs) from 76.3% (2015) → 78% (2025).
🏦 Meanwhile, top MFCs — First National, MCAP & Nesto — manage about 10% of residential loans.
–––––––––––––––––––––… pic.twitter.com/id1d1YoXh6
— Hanif Bayat (@HanifBayat) October 27, 2025
Why Brokers Can Shop the Rate and Still Feed the Banks
Mortgage Professionals Canada, the industry association, said in July 2026 that broker share had reached a new high. Nearly two in five Canadians obtained their mortgage through a broker, 38 percent in its consumer survey, and 48 percent among recent first-time buyers. Bond Brand Loyalty ran the 20-minute online survey of close to 2,000 people across regions between February 5 and 25, 2026.
Access to the best rate was still the top reason, cited by 54 percent of broker users, down five points from 2024. Other reasons were multiple quotes at 33 percent, help with options and process at 31 percent, and a recommendation on which lender to use at 26 percent. Among recent first-time buyers, 40 percent said they used a broker to understand the process, up 14 points from 2024.
Canadians are facing more complex mortgage decisions than they were a few years ago, from rate selection to lender choice to long-term affordability. This research shows that mortgage brokers are increasingly being recognized not only for access to competitive rates, but for the advice and guidance they provide throughout the process.
Lauren van den Berg, President and CEO, Mortgage Professionals Canada, July 24, 2026
Eighty-three percent of broker clients said they would recommend their broker, a five-year high, and 72 percent of those who used a broker for their current mortgage said they would use one again. Fixed-rate loans still dominate, held by 70 percent of mortgage holders. Variable-rate share sat at 26 percent, up three points and the first rise in three years.
The association represents more than 15,000 members and more than 1,000 firms. Close to half of first-time buyers already choose brokers, it said. That is a distribution win for the independent channel. It is not an ownership win. Brokers are paid by lenders, typically through a finder’s fee at funding, so the incentive is to place the file, not to keep a non-bank’s logo on the balance sheet for 25 years. Banks that buy the loan, or that win the renewal, still collect the 1.5 percent.
Branch posters still lose a lot of those shops. Broker desks print below typical Big Six posted rates on the same five-year product, which is why the 38 percent figure exists at all. The gap does not migrate the $2.7 trillion. It migrates the origination, then the loan is packaged, insured, sold or renewed back into a bank.
First National Leaves the Public Market
The independent that actually scaled did not stay independent in the way a rate-war narrative wants. First National Financial Corporation, the parent of a major non-bank originator, underwriter and servicer of prime residential and commercial mortgages, completed the plan of arrangement on October 22, 2025.
THE FIRST NATIONAL TAKE-PRIVATE
- July 27, 2025: First National agrees to a deal with Regal Bidco, a vehicle controlled by private-equity funds managed by Birch Hill Equity Partners and Brookfield Asset Management, at $48.00 a common share in cash.
- July 27, 2025: The company values the equity, including shares the founders roll, at about $2.9 billion.
- October 22, 2025: The arrangement closes. Cash paid for the shares acquired, excluding the founders’ remaining stake, is about $2.2 billion. Common shares are delisted from the TSX.
- October 22, 2025: Stephen Smith and Moray Tawse, the founders, each keep an indirect stake of about 19 percent. Birch Hill and Brookfield hold the remaining 62 percent.
Smith, 74 at the time of the July announcement, had owned 37.4 percent; Tawse had owned 34.0 percent. Each sold about two-thirds of those holdings and rolled the rest. Preferred shares stayed listed. Senior management was left in place. The broker channel was told the desks would not change. What changed is who owns the platform that administers $166.2 billion of mortgages. The largest non-bank name in the 10 percent origination slice now answers to Brookfield and Birch Hill, with the founders as minority partners.
That is a strange kind of competition. The alternative to the six banks became a private-equity asset, funded with new senior notes and run for institutional owners, still feeding insured loans into the same CMHC pipes the banks use.
The Capital Buffer Cut That Favours Deposit Takers
On June 19, 2026, the Office of the Superintendent of Financial Institutions cut the buffer to 3.0 percent of total risk-weighted assets from 3.5 percent. It also narrowed the Domestic Stability Buffer’s range to 0 to 3 percent from 0 to 4 percent. It was the first change in the level since June 2023, and it took effect that day.
The tool applies to Canada’s six domestic systemically important banks, the same six that already dominate the mortgage book. It does not apply to Desjardins, to credit unions under provincial rules, or to mortgage finance companies that fund in the market. OSFI said Common Equity Tier 1 ratios sat well above the new 11.0 percent supervisory expectation, averaging 13.5 percent, with all six above 13 percent. That extra cushion was about $74 billion, or room to expand risk-weighted assets by $673 billion.
By lowering both the level and top end of the range of the Domestic Stability Buffer, OSFI will enable the banking sector to deploy its excess capital in support of Canada’s economic adaptation to new opportunities.
Office of the Superintendent of Financial Institutions, June 19, 2026 news release
OSFI framed the cut as strength, not strain, and pointed to defence, infrastructure, resources and artificial intelligence as places the six might put the capital. Mortgage books were not the headline. They do not need to be. A cheaper capital constraint for the six deposit-takers, after a decade in which their group share rose, is more room to match a monoline on price and still hold the loan.
Insured Loans Cost Banks Almost Nothing in Capital
Default insurance is the quiet public partner in this market. Canada Mortgage and Housing Corporation said in its 2025 annual report that insurance-in-force stood at $471 billion at year-end, up $31 billion from 2024, with an arrears rate of 0.32 percent. CMHC also guaranteed nearly $166 billion in mortgage-backed securities and $60 billion in Canada Mortgage Bonds in 2025. Those guarantees are how a non-bank that does not take deposits still funds an insured file at a rate a bank can live with, and how a bank can treat the same file as low-risk on its own books.
Bayat called residential mortgages, backed by the house, by that insurance, and by a long stretch of stable prices, among the lowest-risk loans a Canadian bank can make. A 1.5 percent return on a $2.7 trillion stock is not a thin business. It is a utility. The six banks can afford to meet a broker quote on an insured purchase because the credit risk has already been sold to CMHC, Sagen or Canada Guaranty, and because the customer may bring a chequing account, a HELOC and the next renewal.
WHY THE RATE WAR DOES NOT MOVE THE STOCK
- Deposit funding: Banks pay for mortgages with cheap retail deposits; monolines pay capital-market spreads and guarantee fees.
- Insurance: High-ratio loans sit behind CMHC or private default insurance, which is why they can be pooled and sold.
- Renewals: The incumbent already has the file, the login and the HELOC, so a 10-basis-point loss on a new purchase can be won back at term.
- The buffer: OSFI’s June 2026 cut gives only the six D-SIBs more room to deploy capital, not the credit unions or the remaining independents.
Foreign banks have had legal room to take retail deposits in Canada for years and have not built a mortgage franchise that shows up in the share table. The constraint is not a ban on competition. It is a product that is safest and cheapest inside a deposit-funded, insurance-wrapped, six-bank system, with brokers as the storefront and CMHC as the backstop.
The shopper can still leave a branch with a better number. The $2.7 trillion mostly cannot. First National’s new owners will keep originating. MCAP will keep servicing. Brokers will keep taking 38 percent of the conversations. The names that hold the book after the sale are the names that held it in 2015, only more so, and they now have a thinner capital buffer standing between them and the next loan.
Disclaimer: This article is news reporting and analysis of Canada’s residential mortgage market and is for information only. It is not mortgage advice, investment advice, or a recommendation to choose a lender, break a term, or buy or sell any security, including bank or mortgage-finance shares. Readers who are borrowing, renewing, or investing should speak with a licensed mortgage broker or advisor and, where investments are involved, a registered financial advisor who can review their own file. Figures for market share, loan balances, capital ratios, and deal terms come from the dated sources cited and will change as lenders report new quarters.

Saquon Barkley’s Hamstring Leaves the Eagles Thin in London

The Online US Passport Still Needs a Witnessed Oath

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-

 NEWS4 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning