BUSINESS
Private Banks Bet on 34% Loan Growth Inside a 15% Cap
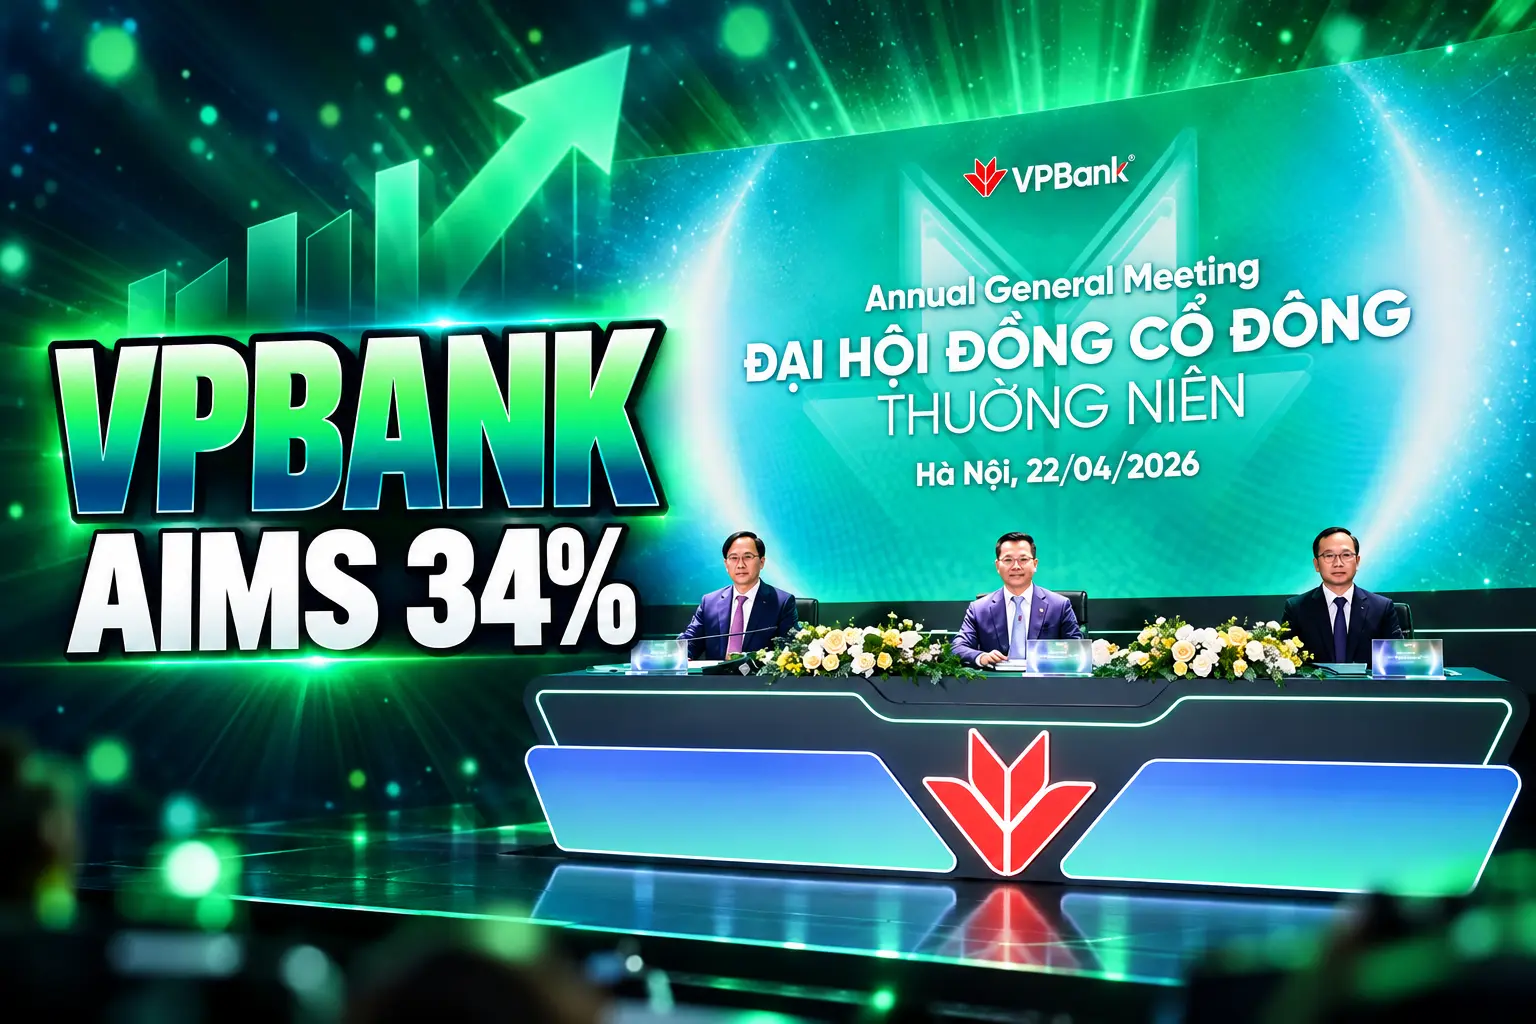
VPBank still wants 34% loan growth in 2026 inside the State Bank’s 15% cap, using extra quota from weak-bank transfers and cheaper risk weights.

VPBank is still aiming for 34% loan growth in 2026 even as the State Bank of Vietnam holds the system to 15%. MB set a similar 35% pace for loans and deposits. The gap looks like defiance until you look at who received extra credit room, and why.
By 30 September, system loans were up only 11.59% from the end of 2025. The parent book at VPBank was already up 24.6% in the first half. The wager is now a fourth-quarter fight over leftover quota.
VPBank Still Wants a 34% Loan Year
Shareholders at VPBank’s 22 April 2026 meeting in Hanoi approved a plan for consolidated credit near VND 1,300 trillion, up 34% from 2025. Group pretax profit is set at VND 41,323 billion, up 35%. Customer deposits and valuable papers are meant to pass VND 1,000 trillion, up 40%.
The same meeting voted to lift charter capital from VND 79.339 trillion to VND 106.243 trillion, first by a share issue from equity to VND 100,000 billion, then by a private sale of more than 624 million shares to a foreign buyer. End-2025 group assets were VND 1,260 trillion, up 36.4%, and group loans stood above VND 961 trillion. The capital ratio was still above 14%.
MB’s board chairman, Luu Trung Thai, told investors on 2 February that the bank wants credit and funding growth around 35% in 2026, above the market average, with profit up 15-20% to about US$1.58 billion. Chief executive Pham Nhu Anh has said fee income “at best makes up around 30%,” so the P&L still leans on loans. OCB put loan growth at 22%. Several mid-size private banks clustered near 20%.
In terms of financial performance, MB expects profit growth of 15-20 per cent, equivalent to approximately $1.58 billion. Member companies are identified as key business spearheads, projected to contribute around 12-13 per cent of the group’s total profit.
Luu Trung Thai, Chairman, MB, investor conference, 2 February 2026
Vietcombank Securities said at the start of the year that the whole sector might land at 16-18%, with “dynamic private banks” still running above 20%. Fitch Ratings later put the system nearer 18%. The State Bank’s published target stayed at 15%, down from a 16% plan in 2025, after credit actually rose 19.1% that year.
Credit Is Up 11.59% With a Quarter Left
Deputy Governor Pham Thanh Ha told the regular government briefing on 3 October that loans across all credit institutions were about VND 20,750 trillion on 30 September, up 11.59% from the end of 2025 and up 16.69% from a year earlier. He said that pace still fits the central bank’s goal for 2026.
Two figures from late August set the scale. On 28 August the stock was VND 20,200 trillion (US$776.5 billion), up 10.2% year to date. Governor Pham Duc An said about 77.3% of outstanding loans were in production and business. Pham Chi Quang, who runs the Monetary Policy Department, has put the credit-to-GDP ratio at 146%, high for a lower-middle-income economy, which is why the 15% cap was sold as a stability tool rather than a growth tool.
The listed-bank tape tells a different story from the system average. At the end of the second quarter, loans at Vietnam’s 28 listed banks totaled VND 15,838 trillion (US$609.1 billion), up 18.2% year on year, 9.2% from the start of 2026, and 5.5% from the prior quarter. Large private banks supplied nearly 55% of that year-on-year rise. BIDV, Vietcombank, and VietinBank together supplied about 29.3%.
THE 2026 CREDIT SPRINT
| Bank | 2026 target | Recorded growth | Window |
|---|---|---|---|
| VPBank | 34% | 24.6% | Parent loans, first half |
| MB | about 35% | 13.2% | Year to midyear, TCBS |
| HDBank | Not disclosed | 21.8% | Year to midyear, TCBS |
| Techcombank | Not disclosed | 15.2% | Year to midyear, TCBS |
| Whole system | 15% | 11.59% | Year to 30 September, SBV |
Year-on-year rates at the end of June were hotter still: 40.6% at VPBank, 37.8% at MB, 32.7% at HDBank, and 25.1% at Techcombank. State lenders grew more slowly on that measure, 14.7% at BIDV, 12.8% at Vietcombank, and 10.1% at VietinBank. ACB rose 17.9%. Sacombank rose 9.8%.
Techcom Securities (TCBS) said Techcombank and MSB, the latter up 11.4% by midyear, had almost used their full 2026 rooms after six months. Second-quarter system flow was about VND 811 trillion, 1.7 times the first quarter. For banks already at the ceiling, the next dong of credit is a regulatory event, not a credit-committee event.
Why VPBank Can Grow Faster Than the 15% Cap
The 15% figure is a system ceiling, not a uniform cap on every license. Rooms are assigned bank by bank against capital, asset quality, and ratings. KB Vietnam Securities noted that a breach of safety tests can shrink a room, which turns quota into a supervisory lever.
The three private banks that took on mandatory transfers of weak lenders received “exceptionally high” rooms to fund that cleanup, TCBS said, and they used them. HDBank’s midyear book was up 21.8%. MB’s was up 13.2%, a long way from a 35% year unless a second allocation arrives. VPBank’s July statement put standalone credit up 24.6% this year to nearly VND 1,060 trillion, with group assets above VND 1,500 trillion, up 19.2% from the end of 2025.
Half of a 34% year is 17%. A 24.6% rise in six months on the parent book is ahead of that line. Group pretax profit for the half was nearly VND 18.9 trillion, up 68% year on year and about 46% of the full-year plan. In the first quarter, group loans had already passed VND 1,000 trillion, up 10.2%, with pretax profit above VND 7,900 billion, up 58%, and deposits near VND 822 trillion, up 11.8%.
Thai tied MB’s 35% aim to “advantages gained from participating in the restructuring of a mandatory transferred bank.” That is the hidden collateral in the March targets. The banks did not invent a 34% year in spite of the State Bank. They booked a year the allocation rules could still permit.
First-quarter rules were tighter for everyone else. The State Bank told lenders not to use more than a quarter of their annual target in the first three months, and it said each bank’s 2026 real-estate credit growth must not exceed that bank’s overall credit growth rate at the end of 2025. In June it then let 25 banks keep extra loans for social housing, industrial parks, and export-processing zones outside those real-estate ceilings.
Circular 14 Cuts Capital Costs on Priority Loans
Quota is only one constraint. Risk-weighted assets are the other. Circular 14/2025/TT-NHNN, in force from mid-September 2025, lowered credit risk weights on the same books the government wants filled, so a dong of farm or social-housing credit consumes less capital than a dong of speculative property.
CIRCULAR 14 RISK WEIGHT CUTS
- Farm and rural loans: The credit risk weight falls from 100% to 50%, which halves the capital a bank must hold against that book.
- SME loans: The weight moves from 90% to an SME credit risk weight of 85% under the new grid.
- Social housing: If the loan-to-value ratio is below 40%, the weight is 20%; otherwise it stays in a 35-50% band, far below ordinary property.
- Commercial property: The weight can reach 150% when a project fails tests on completion, clean title, and collateral value, which makes that book more expensive to grow.
A KIS note on the circular maps social housing risk weights of 20-50% against the older 30-100% band, and it flags the SME cut from 90% to 85%. SSI Research called the circular a step toward international capital rules. SHS said the weights would reroute credit without a new administrative ban. VPBank’s own 2026 plan still puts retail and SME at the center, with unsecured loans meant to rise to 10-11% of the book, and it wants the parent nonperforming-loan ratio under Circular 31 kept below 2.5%.
The cheap-loan headline is thinner than the risk-weight story. Ha said 19 commercial banks have joined a preferential program of about VND 409,000 billion, up from four state banks at the start. Only 10 of them had actually disbursed, about VND 18,600 billion to some 12,900 customers, at rates 1 to 3.6 percentage points below normal. That is about 4.5% of the registered pool sitting on the books. The transfer-bank rooms and the property carve-outs move more credit than the poster program.
Deposits Grew 5.5% While Loans Grew 10.2%
The other half of the wager is funding. TCBS said deposits were up 5.5% over the first eight months, against 10.2% loan growth. Among the 28 listed banks, customer deposits rose 11.9% year on year while loans rose 18.2%. Core funding still grew 18.4%, but a lot of that came from other banks (up 45.4%) and from valuable papers (up 23.5%).
Customer deposits make up about 75-80% of core funding at Vietcombank, BIDV, and VietinBank. The share is 59% at VPBank, 64% at Techcombank, 62% at ACB, and 65% at MB. OCB, Nam A Bank, SeABank, MSB, and TPBank sit around 51-59%. Banks that grow loans faster than retail deposits pay more for wholesale money, and that shows up in the margin.
The sector’s trailing 12-month net interest margin slipped to 2.95%, four basis points below 2025. Yields on earning assets recovered about 35 basis points, but funding costs rose nearly 42. State banks still run NIMs around 2.1-2.7%, a function of sticky deposits and large corporate books. VPBank has already said its NIM fell from 4.6% to 4.53% and could drift toward 4.4% in 2026.
Circular 25/2026/TT-NHNN raises the cap on short-term funds used for medium- and long-term loans from 30% to 40%. The State Bank also let Treasury term deposits count toward mobilized funds in the loan-to-deposit ratio. TCBS said those two changes help state banks most, because they hold the bulk of Treasury cash and face the tightest ratio tests. If the last quarter is a race, that rule set is a late boost for BIDV, Vietcombank, VietinBank, and Agribank, not for the private names that already spent their rooms.
Stage 2 Loans Are Climbing Faster Than NPLs
Bad-loan ratios on the 28-bank tape look calm because the denominator is growing. The nonperforming-loan ratio was 2.02% at midyear, up 14 basis points. The stock of bad loans still rose 17.2% from the start of 2026, to VND 314.3 trillion (US$12.1 billion). Stage 2 loans, the watch list before default, rose faster: VND 213.2 trillion (US$8.2 billion), up 28.3%, with the ratio at 1.37%. Combined Stage 2 through 5 sat at 3.39%. Fifteen of the 28 banks saw their Stage 2 ratio rise in the second quarter.
PRESSURE POINTS IN THE LOAN BOOK
- Group NPL at VPBank: The listed-bank tape puts VPBank at a 3.28% nonperforming-loan ratio and 3.17% Stage 2, with a 56% loan-loss reserve.
- Parent NPL: Under Circular 31 the parent ratio was still around 2% at the end of the second quarter, below the 2.5% target, with the group ratio under 3%.
- HDBank watch list: The nonperforming-loan ratio was 2.79% and Stage 2 loans were about 4.7%.
- Provisions: The 28 banks booked VND 83 trillion (US$3.2 billion) in the first half, up 20% year on year, already about 1.11 times the whole of 2025.
Sacombank is the outlier, with a 7.54% nonperforming-loan ratio and problem loans above 10%, and it accounted for 43.5% of the rise in provisions. Vietcombank still runs a 0.61% bad-loan ratio and a 279% reserve. Techcombank and ACB sit near 1-1.1% with reserves above 100%. Credit at the 28 banks also leaned into longer-tenor, capital-heavy sectors, including property and construction, which lift yield and legal risk at the same time. Corporate bond books jumped 39.9% year on year to VND 257.204 trillion, still only 1.6% of credit.
Deputy CEO Luu Thi Thao said after the first half that VPBank would not chase every market opening and would stay inside its risk appetite. “With the strong foundation established in H1 2026, we are confident in sustaining growth momentum and achieving our committed goals, as endorsed by the Annual General Meeting,” she said. The parent still wants credit growth above 30% for the year. That sentence only works if the State Bank tops up the room, and if Stage 2 stays a watch list rather than a pipeline into default.
What Extra Quotas Mean for the Last Quarter
TCBS has already named the two constraints that decide the rest of 2026: more quota, and the ability to raise money. Banks that have spent their rooms wait on Official Letters. Banks that still have room still need deposits, papers, or foreign funds to use it. Nine-month GDP was up 9.01%, and the third quarter rose 9.95%, so demand is not the missing piece. The government still wants full-year growth above 10%.
Ha said the State Bank has told lenders they may keep new loans for social housing, industrial parks, export zones, hotels, and resorts outside the real-estate totals that must be controlled, and that large, multi-province projects can sit outside the extra-growth count as well. That is how a 15% year still feeds a double-digit GDP plan without a public rewrite of the cap.
HOW THE ROOM WAS BUILT
- September 2025: Circular 14 takes effect and cuts risk weights on farm, SME, and social-housing loans while lifting weights on weak commercial property.
- January 2026: The State Bank sets a 15% system target and limits first-quarter growth to a quarter of each bank’s annual room.
- 22 April 2026: VPBank’s meeting locks in 34% group credit growth and the capital rise to VND 106.243 trillion.
- June 2026: Twenty-five banks may keep extra social-housing and industrial-park loans outside 2026 real-estate ceilings.
- 17 July 2026: VPBank reports parent loans up 24.6% in the first half, to nearly VND 1,060 trillion.
- 30 September 2026: System loans reach about VND 20,750 trillion, up 11.59% year to date, which Ha said still matches the year’s goal.
Loan growth in 2026 is clustering at the private banks that took weak lenders, while several mid-tier names had already chewed through their rooms by midyear. That turns the last quarter into a rationing problem. VPBank can still print a 34% year if the next allocation lands. MB’s 13.2% midyear print makes 35% a steeper ask. The 15% cap was never the whole rulebook, and the banks that treated it that way are the ones now waiting in line.
Ha’s 11.59% year-to-date print still sits inside the published cap, which is why the central bank can call the year orderly while VPBank’s parent book runs at 24.6%. The last three months decide whether that split was a design or a miss.
Disclaimer: This article is news reporting and analysis of bank credit targets, State Bank rules, and published results. It is for information only and is not investment advice, a recommendation to buy or sell any bank share, or a forecast of profits, dividends, or loan quality. Readers who may act on figures for lending, deposits, or securities should consult a licensed financial adviser or credit officer who can review their own position. Loan stocks, growth rates, capital ratios, and quota status are those given by the banks and the State Bank of Vietnam in the documents and briefings cited, and they can change as later allocations and audited accounts are issued.

Saquon Barkley’s Hamstring Leaves the Eagles Thin in London

The Online US Passport Still Needs a Witnessed Oath

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-

 NEWS4 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning