BUSINESS
Green Dot Still Banks Apple After a $44 Million Fed Fine
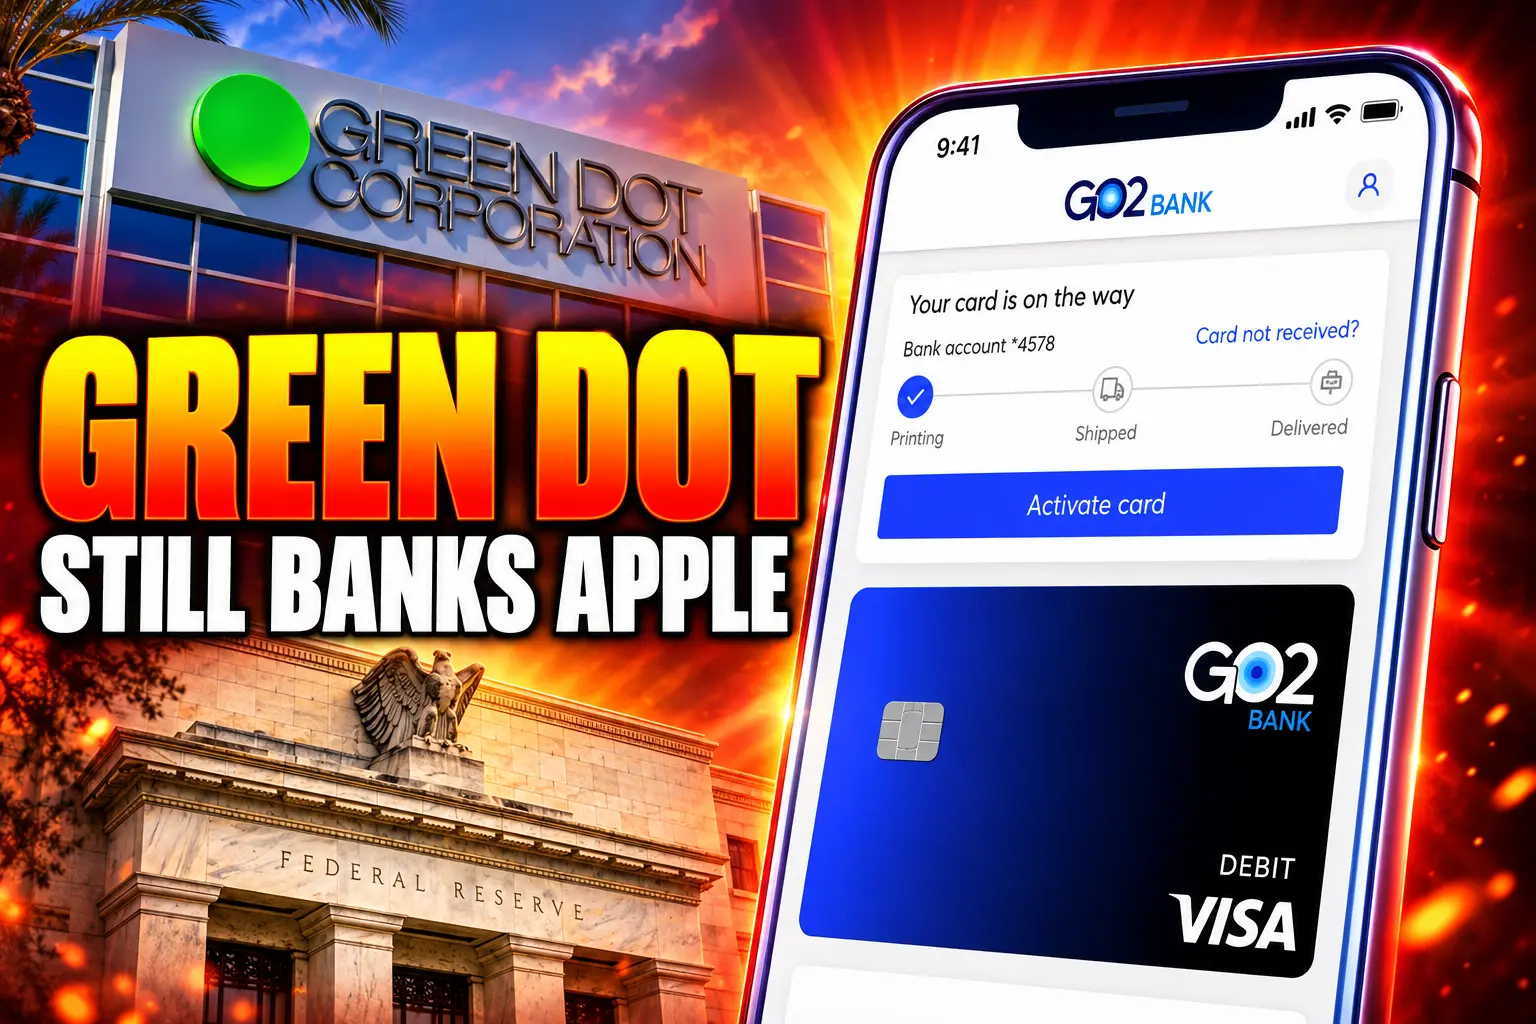
The Fed’s $44 million Green Dot order did not shake Apple Cash or Walmart MoneyCard, and that same bank is now being split in a sale.

The Federal Reserve fined the firm $44 million on July 19, 2024, for prepaid-card and tax-refund practices it called unfair or deceptive. The civil penalty was due on the day the Board signed the order, wired to the Federal Reserve Bank of Richmond for the U.S. Treasury.
The order stayed on Green Dot Bank in Provo, Utah, and on Green Dot Corporation in Austin. Walmart later locked in the MoneyCard through January 31, 2033. Apple Cash still clears through that bank, and shareholders have voted to sell the charter to CommerceOne Financial while a private buyer takes the non-bank rails.
The Fed Wrote Five Counts Into a $44 Million Order
Examiners from the Federal Reserve Banks of San Francisco and Dallas had already flagged weak consumer-compliance and Bank Secrecy Act controls. After consumer complaints, the Board and the San Francisco Reserve Bank reviewed general-purpose reloadable cards and tax-refund payment services run with a third-party tax preparer. The review produced five unfair or deceptive counts under section 5 of the Federal Trade Commission Act, plus a demand that the bank rebuild its anti-money-laundering program.
THE FIVE CONSUMER COUNTS
| Count | Period | What examiners found |
|---|---|---|
| Fees on empty accounts | November 2017 to January 2021 | Card packs and agreements said a zero-dollar account would close; many stayed open and kept taking monthly fees |
| Phone registration | June 2019 to December 2020 | Packaging still promised signup by phone after the bank dropped that option, so people without internet could not activate cards |
| Unemployment blocks | May 2020 to June 2020 | Legitimate Washington state jobless-benefit customers were locked out with no reasonable way to reopen the account |
| Stuck authorization holds | August 2020 to at least September 2020 | A processor data move left holds, including at gas pumps, in place for days after the sale settled |
| Tax refund processing fee | January 2017 to December 2022 | Santa Barbara Tax Products Group hid a separate refund-processing fee behind links and drop-down small print |
Green Dot consented without admitting or denying the Board’s allegations, and it waived a hearing. The Board had approved the package on July 18, 2024, with Chair Jerome Powell, Vice Chair Philip Jefferson, Vice Chair for Supervision Michael Barr, and Governors Michelle Bowman, Lisa Cook, Adriana Kugler, and Christopher Waller recorded on the vote. The public release went out at 1:30 p.m. EDT the next day.
WHAT THE ORDER REQUIRED NEXT
- AML rewrite: Within 90 days the bank had to file a revised Bank Secrecy Act program, including a risk assessment, a customer-identification process, independent testing, and a compliance officer with real autonomy and staff.
- Suspicious activity: The same 90-day clock covered a written program for spotting and reporting suspicious transactions, with documented thresholds and a paper trail for every alert the bank closed.
- Lookback: An independent firm acceptable to the San Francisco Reserve Bank had to review transaction monitoring from August 1, 2021, through October 31, 2022, and report to that Reserve Bank.
- Consumer program: The holding company had to hire an independent consultant to tighten consumer-compliance risk management and to trace the root causes of complaints.
- The check: The $44 million civil money penalty was payable on execution by Fedwire of immediately available funds to the Richmond Fed.
Those program clocks, not the headline fine, are what a later buyer of the bank actually inherits. The five consumer counts had end dates between 2020 and 2022. The consent order is the overlay that remains.
Washington Jobless Cards Sat Frozen With No Way Back
The press release spoke of unemployment benefits in general. The signed order is narrower and harsher. From May 2020 through June 2020, at the peak of pandemic jobless claims, the bank blocked legitimate customers receiving Washington state unemployment insurance benefits and lacked reasonable policies for those customers to cure the blocks and reach their money.
That is the load-bearing harm in the file. Prepaid cards were how many people without a traditional checking account actually received state benefits. A fraud filter that cannot be unwound turns a prepaid account into a trap, because the customer’s rent money is already on the card and there is no other rail. The order also found that a third-party processor’s data migration, from August 2020 through at least September 2020, left authorization holds sitting on accounts for days after the underlying sale, including at gas-station pumps, which cut available balances again.
George Gresham, then chief executive and president, treated the package as a matter the company had already priced in. Green Dot had told investors earlier in 2024 that a public enforcement action was coming.
As we shared previously, the order relates to practices in place years ago, and we have taken and will continue taking meaningful steps to correct and remediate those issues, including significant updates to our processes, our product packaging and marketing, our management team and our compliance programs.
George Gresham, Chief Executive Officer, Green Dot Corporation statement, July 19, 2024
He was describing practices in place years ago, and the dated counts support that calendar. The open question the order left is not whether 2017 packaging copy was still on shelves in 2024. It is whether the bank’s method for freezing an account, and for letting a real customer back in, actually changed.
Why Walmart Still Uses Green Dot After the Fine
Walmart did not drop Green Dot after the fine. In 2025 the companies extended the Walmart MoneyCard program through January 31, 2033, with Green Dot Bank still the issuing bank and program manager for the prepaid account sold in Walmart stores. The retailer has used that rail since 2006, and the 2025 extension pushed the relationship well past the 2027 end date on the prior deal.
Green Dot’s annual report still calls Walmart its largest retail distributor. The MoneyCard is the store-brand prepaid product a shopper can buy at the register, reload in cash, and spend on the Visa or Mastercard networks, with the deposit sitting in an FDIC-insured Green Dot Bank account. For Walmart, the card is a checkout and cash-in tool, not a compliance trophy. Switching issuers would mean re-carding a huge prepaid base and rebuilding in-store reload operations. The Fed order did not force that choice.
That is the second punch the July 2024 headline missed. The Board took $44 million out of the bank holding company and put independent reviewers inside the shop. It did not take Apple or Walmart off the books. The consumer-facing brands kept a cheap, familiar prepaid rail, and the supervised bank kept the consent order.
Apple Cash Still Clears Through the Same Bank
Green Dot’s latest annual report named Apple, Intuit, Dayforce, and Amazon among its largest customers. The Apple relationship that ordinary users actually touch is Apple Cash, the peer-to-peer balance inside Apple Wallet. Green Dot Bank’s own account was still answering Apple Cash complaints on October 2, 2026, which is the simplest proof that the rail had not moved.
The complaint pattern on that rail matches the 2020 finding more closely than the company would like. People describe send functions shut off with no notice, no case number, and no documented way to reopen the account. Support staff point them to a private message and stop there. One official reply in July 2026 asked a locked-out user to send details so “a Customer Support representative will review and respond,” which is a ticket, not a cure path. Another customer, in September 2026, said identity verification failed, the account was locked, and two representatives would not say whether it would be unlocked.
Banks are allowed to freeze accounts they believe are tied to fraud, and they are often barred from spelling out a suspicious-activity report. That legal silence is real. It is also the exact gap the Fed wrote into count C: a freeze without reasonable policies for a legitimate customer to get back in. Two years after the order, that is still how Apple Cash users describe a hard lock. The louder problem on the rail is not the 2024 civil penalty. It is a block that does not come with a way home.
The Tax Refund Fee Lived in the Fine Print
Santa Barbara Tax Products Group, a wholly owned Green Dot unit known as TPG, sat in the middle of “pay nothing out of pocket” tax filing from January 2017 through December 2022. A major tax preparer’s site let customers have preparation fees taken from the IRS refund. The site did not clearly and conspicuously disclose that those customers also owed a separate tax-refund processing fee. TPG received a small slice of that fee. By 2022 it had added some website fixes. The Fed still treated six years of buried disclosures as a deceptive act, and it held the holding company responsible for the fee language on the tax preparer’s site.
HOW THE FEE WAS BURIED
- The pitch: The tax site offered a way to “pay nothing out of pocket” by taking the preparation charge from the refund.
- The extra charge: Customers also owed a separate refund-processing fee that was not shown clearly beside that pitch.
- The hide: The fee sat behind hyperlinks at the bottom of pages or inside drop-down menus of small-print statements.
- The cut: Under the contract with the tax preparer, TPG took only a small portion of the processing fee, but Green Dot still owned the disclosure.
The order never names the tax software company. Intuit’s own help pages, updated into 2026, still tell TurboTax customers that if they pay with their refund, a bank takes the TurboTax fees plus a $40 processing charge, and they name Santa Barbara Tax Products Group, a Green Dot unit, as that bank. In the first quarter of 2026 Green Dot processed 7.78 million tax refunds, down from 7.98 million a year earlier, so the refund-transfer business was still a live season, not a closed chapter of the 2024 order.
Gresham Left, Then the Company Went on the Block
On March 7, 2025, Gresham ceased serving as chief executive and president of Green Dot and of Green Dot Bank and left the board. William I. Jacobs, the board chair since 2016 and a former interim chief executive, came back as interim CEO. Chris Ruppel, the chief revenue officer, became interim president of the company and interim chief executive of the bank. The same day, the board said it had hired Citi to explore potential strategic alternatives.
By the May 11, 2026 earnings release, Jacobs was speaking as chief executive, not as a caretaker. First-quarter operating revenue was $656 million, up 17% from a year earlier. The company counted 3.43 million active accounts and about $34 million of cash at the holding company on March 31, 2026. It also said it had received early termination of the Hart-Scott-Rodino waiting period on the sale and had filed applications with the bank regulators. It skipped a guidance call because of that deal.
The consumer business was not the growth engine. Retail prepaid kept losing ground as shoppers moved to digital accounts, and Green Dot cut back direct-to-consumer marketing for much of 2024 and 2025. What was growing was banking-as-a-service, the white-label bank behind other brands, plus tax processing. That mix is why a consent order on prepaid cards and AML still matters after the old card packs are gone. The bank behind Apple Cash and the MoneyCard is the same charter that has to run the rebuilt BSA program.
An Alabama Bank Inherits the Consent Order
On November 23, 2025, Green Dot signed an agreement and plan of merger with CommerceOne Financial Corporation of Birmingham, Alabama, and a separation agreement with an affiliate of Smith Ventures. CommerceOne would take Green Dot Bank. Smith Ventures would buy and take private the non-bank fintech and embedded-finance business, at a $690 million cash price in the transaction materials, and keep Green Dot Bank as that business’s exclusive issuing bank under a long-term contract. The new public holding company would own both CommerceOne Bank and Green Dot Bank.
THE PATH FROM THE FINE TO THE SPLIT
- July 18, 2024: The Federal Reserve Board approves the Green Dot cease-and-desist order and civil money penalty.
- July 19, 2024: The Board publishes the $44 million order; Gresham says the company expected the action.
- March 7, 2025: Gresham leaves; Jacobs and Ruppel take the top jobs; Citi starts a strategic review.
- 2025: Green Dot and Walmart extend MoneyCard, with Green Dot Bank still the issuer, through January 31, 2033.
- November 23, 2025: Green Dot, CommerceOne, and Smith Ventures sign the split-sale agreements.
- June 23, 2026: Green Dot and CommerceOne stockholders vote the deals through, with closing then expected in the third quarter of 2026 if the Fed, Alabama, and Utah sign off.
At Green Dot’s special meeting on June 23, 2026, more than 99% of the shares voted were in favor, about 72% of the 56.7 million Class A shares outstanding on the May 15, 2026 record date. CommerceOne’s meeting recorded 100% of votes cast in favor, about 69% of its outstanding shares. The companies said remaining conditions included approval by the Board of Governors, the Alabama State Banking Department, and the Utah Department of Financial Institutions.
We appreciate the strong support of Green Dot and CommerceOne shareholders for a transaction structure designed to allow the fintech and banking businesses each to operate with greater focus.
Blake Davidson, Managing Partner, Smith Ventures, June 23, 2026 joint statement
Focus is the pitch. The structure is a supervised Utah prepaid bank, still under a 2024 consent order, being folded into a new public holding company while the partner-facing software is taken private. Shareholders voted to approve that split. They did not vote the Fed order off the charter. Whoever files the next Green Dot Bank Call Report will file it with that order still in the file, unless the Board has ended it in a later notice that has not been posted.
The $44 million already went to the Treasury. Apple Cash users who cannot send money, and MoneyCard holders who still reload at a Walmart register, are living with the bank that remains.
Disclaimer: This article is news reporting and analysis of a Federal Reserve enforcement action and related company filings. It is for information only and is not legal, investment, tax, or banking advice. It does not recommend buying, selling, or holding Green Dot, CommerceOne, Walmart, Apple, or any other security, and it does not tell any reader how to handle a frozen prepaid, Apple Cash, or tax-refund account. Readers who need advice on a specific account, claim, or transaction should consult a qualified attorney, a licensed financial adviser, or their bank’s regulator before acting. Figures, partnership terms, and deal status reflect the cited Federal Reserve order, company statements, and filings as those documents stood, and they can change if the Board, a court, or the parties issue a later notice.

Saquon Barkley’s Hamstring Leaves the Eagles Thin in London

The Online US Passport Still Needs a Witnessed Oath

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-

 NEWS4 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning