BUSINESS
The Free Velocity Banking Calculator Still Needs a HELOC
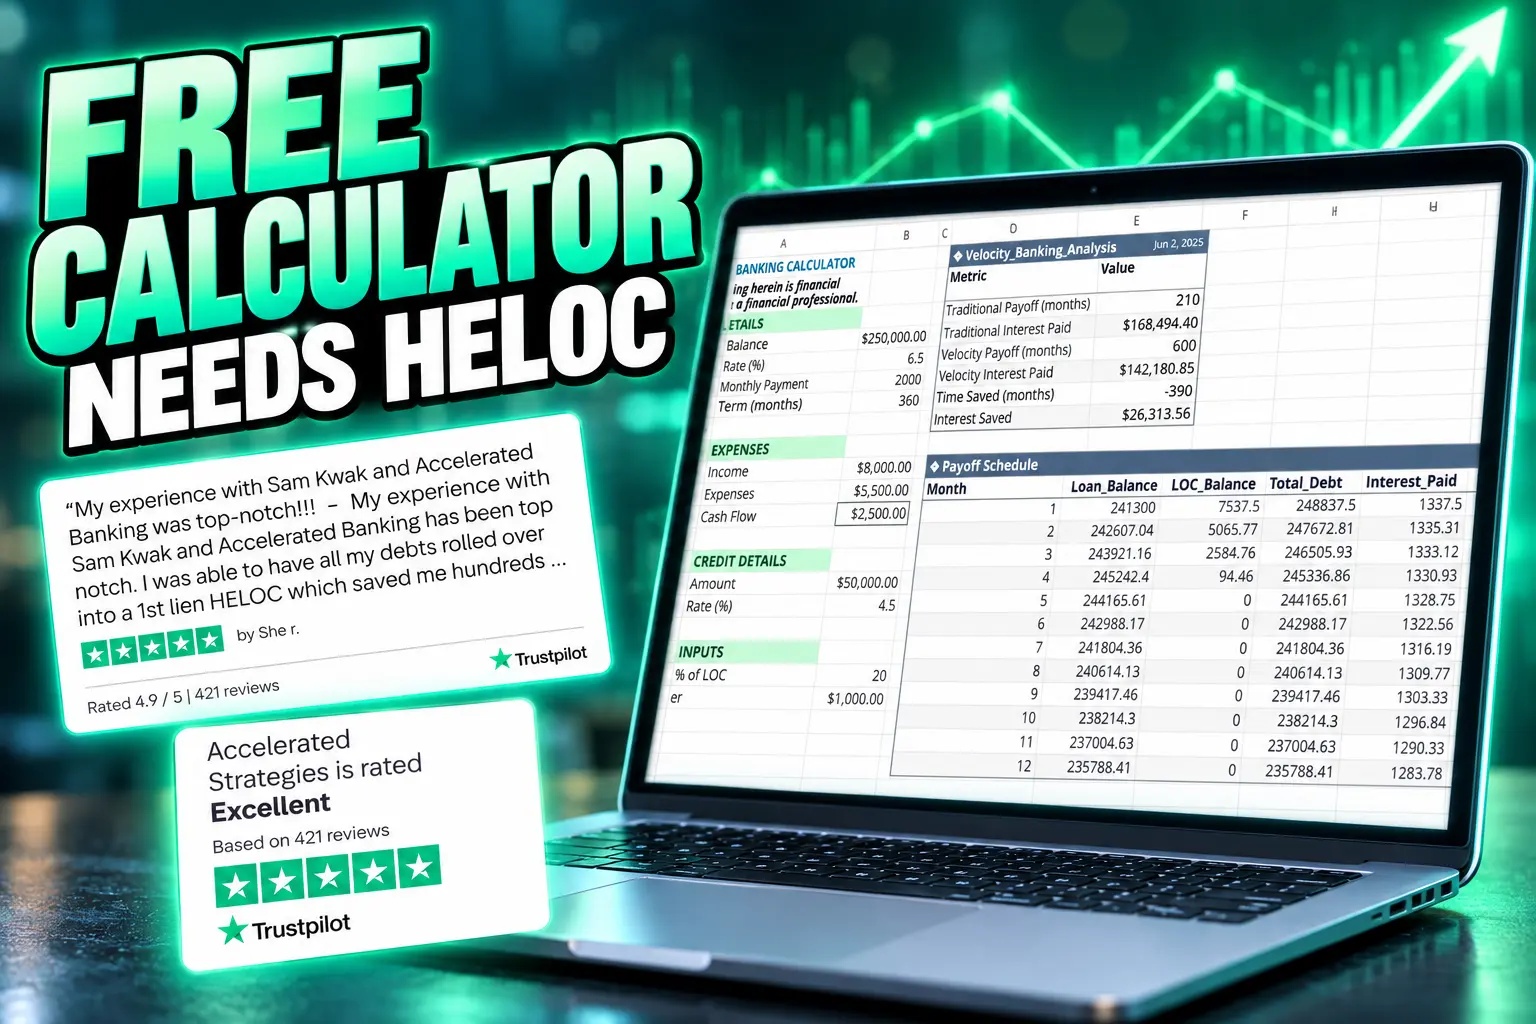
Accelerated Banking’s free velocity banking calculator models HELOC payoff math, but extra principal at the same surplus does most of the work.

Accelerated Banking released a free velocity banking calculator that lets U.S. homeowners model a home-equity payoff plan from their mortgage, income, and expenses. Sam Kwak, co-founder and a Certified Financial Education Instructor, called the tool an excellent way to test the strategy’s validity. The test that actually decides validity is whether that plan beats sending the same leftover cash straight to principal.
The Hendersonville, Tennessee, firm pairs the calculator with a complimentary webinar. Behind both sits a consulting program of video courses, software, and coaching built around a home equity line of credit, or HELOC.
Accelerated Banking’s Free Calculator Opens a Sales Door
Users enter mortgage details, income, expenses, and a proposed line of credit. The company says the tool returns estimated savings within minutes. Kwak also called it “a massive eye-opener to homeowners” interested in faster debt payoff.
an excellent way to test the strategy’s validity and advantages
Sam Kwak, co-founder, Accelerated Banking
Accelerated Strategies, the 2021 consulting company the Kwak brothers formalized after years of videos, states a mission of helping one million American families in 10 years. Its site books consulting calls and lists qualification specialists beside financial coaches. The firm is not a bank and does not make loans. A client contract for the older Accelerated Banking program promised a 5-week on-demand course, lifetime software, a private group, and, on the 1:1 tier, private coaching, with a 180-day money-back promise if the mortgage balance does not fall faster than the “traditional way.”
That last clause is the whole argument. Faster than the original schedule is easy once surplus exists. Faster than extra principal at the same surplus is the claim that has to clear.
How Velocity Banking Moves the Same Surplus
Velocity banking is a cash-flow routine, not a new loan product. A homeowner opens a HELOC, uses it to make a large principal payment on the mortgage, then runs paychecks and bills through the line so the drawn balance falls, and repeats. Promoters call the lump sum a chunk and the paycheck step parking.
THE HELOC LOOP
- Open the line: Borrow against home equity, usually at a variable rate, with a draw period that later turns into repayment.
- Chunk the mortgage: Draw a lump sum and send it to principal so the first-lien balance drops in one hit.
- Park the paycheck: Deposit income on the HELOC so daily interest is charged on a lower balance for part of the month.
- Pay bills off the line: Living costs raise the HELOC balance again as the month runs.
- Repeat: When the line is worked down, draw another chunk and start over for as long as the lender leaves the line open.
A HELOC charges simple interest on the daily balance, which is the only mechanical difference from a standard mortgage. That difference can shave a little interest if the line is cheap, the surplus is real, and the homeowner never treats the credit as spending money. It does not create the surplus. If the household has no leftover cash after bills, the loop has nothing to cycle.
Extra Principal Does Most of the Work
Ryan Alexander Rybarczyk, a senior loan officer, put the arithmetic in one line: “The savings come from the extra principal, not the HELOC.” A checking account can send that principal. The line adds a second product, a second rate, and another claim on the house.
One homeowner documenting a six-month HELOC plan said he had paid down $40,000 of mortgage principal, around $6,500 a month. That monthly figure is surplus. The same $6,500 sent as extra principal, with no draw and no variable rate, would have cut the first-lien balance too. Replies to that update asked the blunt question the calculator should force: why not just use the cash flow on the loan you already have?
THREE WAYS TO USE THE SAME SURPLUS
| Path | Needs a HELOC | Rate on the extra dollars | Lender can cut access | Added claim on the house |
|---|---|---|---|---|
| Extra principal | No | Keeps the mortgage rate | No | No new lien |
| Velocity banking | Yes | HELOC variable rate | Yes | Yes, on the line |
| Scheduled payments only | No | Mortgage rate, no extra dollars | No | Original mortgage only |
Daily-balance interest on the line can add a small bonus when the HELOC is cheaper than the mortgage and the paycheck sits there for many days. When the line costs more than the mortgage, that bonus flips. The homeowner pays a spread for the privilege of routing money through a second account.
A 7.29% Line Against a Locked-In Mortgage
The firm’s pitch says homeowners can shrink a 15- to 30-year loan to 5 to 7 years without refinancing, changing income, or cutting expenses. Without refinancing means the first mortgage stays in place. For anyone who borrowed in the early 2020s, that first mortgage is often far cheaper than a new line of credit.
RATES AROUND THE TOOL
- HELOC average: The St. Louis Fed’s Bankrate series shows a national average HELOC rate of 7.29% as of September 30, 2026.
- New 30-year: Freddie Mac said the 30-year fixed rate averaged 7.28% as of October 1, 2026, up from 7.03% the prior week and 6.34% a year earlier.
- 15-year fixed: The same survey put the 15-year average at 6.60% on October 1, 2026.
- The gap: One basis point separates the HELOC average from the new 30-year average, and a locked 3% first mortgage sits far below both.
A strategy that “does not refinance” is aimed at people who already have a rate they do not want to give up. Drawing a 7.29% line to prepay that cheaper loan replaces low fixed debt with higher variable debt for as long as the chunk is outstanding. The mortgage interest you avoid on the chunked dollars has to beat the HELOC interest you pay while you work the line back down. At today’s averages, that bar is barely there for a new mortgage and is gone for a cheap existing one.
Home Equity Lines Freeze When Values Slip
The Consumer Financial Protection Bureau’s HELOC explainer is blunt about collateral. If you fall behind, you could lose your home. The same page says lenders may block new draws if the house value falls a lot, and may freeze the line if they decide your finances no longer support the payments.
If you fall behind or can’t repay the loan on schedule, you could lose your home.
Consumer Financial Protection Bureau, HELOC explainer
The Draw Period Is Not Permanent
Most HELOCs let you borrow during a draw period, often about 10 years, then shift you into repayment, often 10 or 20 years. The bureau says monthly payments are often much higher once repayment starts, and some plans can demand the full balance. HELOCs usually carry a variable rate, so the payment can move month to month. A routine that depends on redrawing stops when the draw period ends or when the lender cuts the limit. Regulation Z, at 12 CFR 1026.40, lists the grounds a creditor may use to freeze or reduce a home-equity plan, led by a significant drop in the home’s value.
That is not a rare clause from 2008 folklore. It is in the current rule. A calculator that projects a 5-to-7-year payoff has to assume the line stays open for every chunk in that window.
Mortgage Acceleration Does Not Qualify for the Interest Deduction
The IRS says HELOC interest may be deductible when the money is used to buy, build, or substantially improve the home that secures the loan. On the same FAQ, interest is not deductible when that debt pays personal living expenses, such as credit card balances. Routing a line through household bills and then onto a mortgage is not a home improvement. For loans taken after December 15, 2017, deductible home interest also sits under a combined $750,000 cap ($375,000 if married filing separately). A pitch that still talks about writing off the line as if it were 2016 tax law is selling a deduction the code does not give this use.
Sam Kwak’s Webinar Still Promises 5 to 7 Years
Sam and Daniel Kwak grew up in Chicago after their father was called to minister to Korean immigrant families in 1999. Sam started a mobile DJ business in 2012. In early 2016 they found the Accelerated Payoff method at a seminar, used it on their own credit-card debt, and by 2017 they say they had done more than $5 million in real estate deals and begun posting the method online. Accelerated Banking was launched as a company in 2019. Accelerated Strategies, with Daniel as chief executive and Sam as chief growth officer, was formalized in 2021. The about page says the firm ranked No. 1695 on the 2024 Inc. 5000 list of fastest-growing U.S. companies, and its seminar copy says more than 4,000 homeowners have been helped.
HOW THE FIRM GOT TO A FREE TOOL
- Early 2016: The brothers learn the Accelerated Payoff method and apply it to their own debt.
- 2017: They begin sharing the method online after more than $5 million in real estate deals.
- 2019: Accelerated Banking launches as a company aimed at faster mortgage payoff.
- 2021: Teachings move into Accelerated Strategies, with consulting, software, and a community.
- 2024: The company says it placed No. 1695 on the Inc. 5000 list.
- The calculator release: A free modeling tool and a complimentary webinar feed the same consulting offer.
Seminar language still says the method works without refinancing, without a raise, and without cutting expenses. The surplus has to come from somewhere. If expenses and income do not change, the only dollars that accelerate payoff are dollars that were already leftover, plus whatever a household stops spending because the tracking is stricter. Discipline can be worth paying for. A HELOC is a separate price for that discipline.
A Fair Test Puts Extra Payments Beside the HELOC
Kwak is right that homeowners should test the method before they draw. A fair run uses the same surplus on two paths, stresses the HELOC rate up 2 or 3 points, and asks what happens if the lender freezes new draws in year three. It also asks whether the household will treat the line as a sweep account. Equity temptation is the failure mode that even promoters admit: the available credit sits there, and a kitchen or a car can erase a year of chunks.
WHERE EXPERTS DISAGREE
- Accelerated Banking: The calculator and webinar can show a path to a 5-to-7-year payoff without refinancing, and Kwak presents that as a test of the method’s validity.
- Rybarczyk and the extra-principal camp: Almost all of the faster payoff is the surplus, which a checking account can send, while the HELOC adds variable-rate cost and another lien.
The calculator is free. The line of credit is not. A leftover $6,500 a month starts reducing principal the day it hits the mortgage servicer, with no draw period to outlast and no freeze clause to survive.
Disclaimer: This article is news reporting and analysis of a publicly offered calculator and a mortgage-payoff method, and it is for information only. It is not investment, tax, legal, or mortgage advice, and it is not a recommendation to open a HELOC, prepay a loan, buy a course, or change a repayment plan. Readers should talk with a licensed financial planner, tax professional, and housing counselor who can review their full income, equity, and loan documents before acting. Interest rates, tax rules, product terms, and the company’s offers can change from the figures and pages cited here.

Saquon Barkley’s Hamstring Leaves the Eagles Thin in London

The Online US Passport Still Needs a Witnessed Oath

Ken Urker Died on His Birthday With No Cause Named

FOX Ices Portnoy After Ohio State’s Access Fight

Micron’s Record Memory Profits Lock RAM Tight Through 2028

Musk’s $914 Billion Lead Is a Public SpaceX Bet

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Free Live Sports Streaming in 2026: What to Watch Without Cable

Endgame Encore’s $86 Million Trial for Infinity Vision

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 BUSINESS4 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 NEWS2 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 SPORTS3 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-

 ENTERTAINMENT4 weeks ago
Sterling Point Holds No. 2 on Prime Video After 32 Days
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 ENTERTAINMENT3 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-

 NEWS4 weeks ago
G20 Cheers AI Investment After Bailey’s Frontier Cyber Warning