NEWS
Banks Keep Adding Google Pay as QR Ph Dominates
Philippine banks still add Google Pay even as Visa puts usage in single digits and QR Ph outruns debit and credit cards.

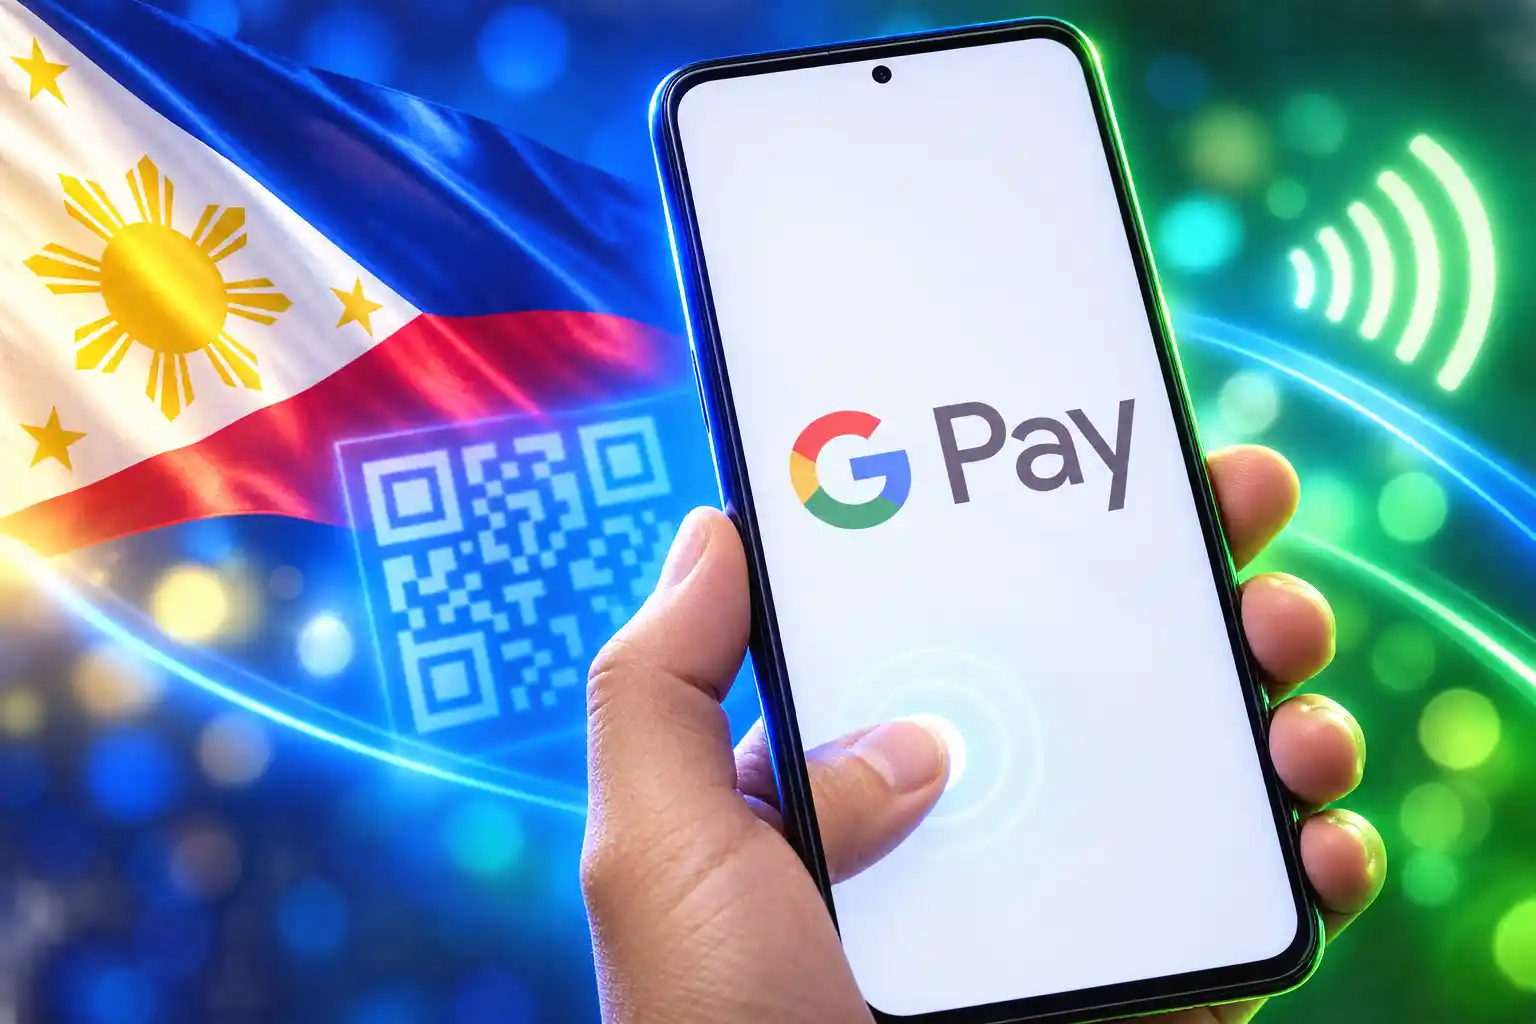
Google Pay went live for Android users in the Philippines on November 18, 2025, with nine banks and e-money issuers offering tap-to-pay through Google Wallet. In June 2026, Visa’s Philippine country manager still put the service in single digits of total payments.
Issuers kept turning the feature on anyway. The product rides card networks and NFC readers, while QR Ph already took the everyday till.
A Tap Wallet in a Scan Country
Google Wallet stores a debit or credit card on an NFC Android phone or Wear OS watch, then pays at any terminal that already takes a contactless chip card. Online and in-app checkout uses the Google Pay button. Launch-day web partners included Shopee plus merchants on PesoPay and PayerMax, with 2C2P, PayMongo, PayRex, Maya, and Sephora listed to follow.
Visa pushed the Android launch first because Android accounts for roughly 80% of local smartphones, according to Jeffrey Navarro, country manager for Visa Philippines. The security pitch is tokenization. Paymentology, GoTyme Bank’s issuer processor, says a unique digital token during each tap stands in for the primary account number, and a dynamic cryptogram rides with it, so the merchant never receives the real card number.
That is a card-network product. It does not replace QR Ph, InstaPay, or the GCash and Maya apps Filipinos already open at the counter. Bangko Sentral ng Pilipinas also treated Apple Pay and Google Pay as outside the operators-of-payment-systems net, because they do not hold customer funds, which removed a licensing queue that slows local wallets.
Visa Still Puts Usage in Single Digits
Six months after launch, Navarro told reporters the service was “not too big yet,” even as month-on-month use over physical cards was rising. He put Google Pay in “the single-digit space” of total payments and said that pattern matched other countries where the wallet had just opened.
We’re still waiting for other players, other banks, and slowly you can see some of them are already announcing as well.
Jeffrey Navarro, country manager, Visa Philippines
He argued the wallet gets sticky only when people use it for ordinary errands, not the occasional tap. “Normally, you see it become stickier once it is used for everyday payments,” he said. “So, once that ecosystem is in place, we expect to see it ramp up.”
Visa still spent the next quarter signing more card products. In September 2026 it expanded Google Pay across Maya’s Visa wallet cards, physical and virtual, after Maya credit cards had been live since November 2025. Maya Group president and Maya Bank co-founder Shailesh Baidwan said the add-on lets customers pay with phones they already carry, at shops, on public transport, and at tourist spots.
The tourist lane is the one QR does not automatically win. Visa research circulated at launch found 97% of Asia-Pacific travellers intend to carry cards and 17% plan to bring foreign currency, while 44% of tourists in the Philippines reported payment trouble, often because a merchant would not take the instrument they had. A later Maya-Visa note put mobile or smart-device preference at 71% of Asia-Pacific consumers. Those figures explain why issuers keep provisioning Wallet even when the domestic till still wants a scan.
Nine Launch Partners, Then BPI and Maya Debit
Paymentology named the nine banks on launch day as China Banking Corporation, EastWest Bank, Rizal Commercial Banking Corporation, Union Bank of the Philippines, GoTyme Bank, GCash, Maya Bank, Wise Philippines, and Zed Financial PH. Visa’s first issuer set was seven of those names: Chinabank, EastWest, GoTyme, Maya, RCBC, UnionBank, and Wise, with Mastercard and GCash following.
Google Wallet’s Philippines issuer list still shows those same nine institutions. Banks have since said they switched on extra card products that the public table has been slow to spell out.
GOOGLE PAY ISSUERS SINCE NOVEMBER 2025
| Issuer | Launch window | What changed later |
|---|---|---|
| Chinabank, EastWest, RCBC, UnionBank, GoTyme, GCash, Maya Bank, Wise, Zed | November 18, 2025 | Core launch set of nine |
| EastWest Bank | Credit cards at launch | Visa debit added March 4, 2026 |
| Bank of the Philippine Islands | Not in the launch nine | Debit Mastercard live April 15, 2026 |
| Maya Bank | Visa credit at launch | Wallet cards, physical and virtual, September 2026 |
| Security Bank | Not live | Targets second half of 2027 |
EastWest chief executive Jerry Ngo said debit on Google Pay “fits naturally into how they live, travel, and shop.” BPI president and chief executive Jose Teodoro Limcaoco had already tokenized the bank’s cards and told reporters it would be crazy for a bank not to join once the wallets were in the market. BPI’s debit Mastercard enrollment is a camera scan or manual entry in Wallet, then an SMS one-time password.
GCash sits in two different places, which confused people on day one. Testers said a GCash Mastercard would not provision, and the GCash app had no obvious Wallet button. GCash’s own desk told users they can link GCash to Google Pay for checkout, a path that is not the same as storing the GCash Mastercard as a tap card. Select users later got a biometric link that skips typing the PAN. The wallet that owns QR still treats Google Pay as an add-on, not a replacement home screen.
How QR Ph Beat Cards in 2025
The central bank’s 2025 e-payments measurement puts digital channels at 64.69 percent of retail payment volume, up from 57.45% in 2024. By value, digital’s share went the other way, to 53.32% from 58.98%. High-count, low-value pings are doing more of the work, which is QR’s terrain.
THE 2025 TILL, IN BSP FIGURES
- Volume share: Digital payments were 64.69% of retail transactions, 7.24 points higher than 2024.
- Value share: Digital fell to 53.32% of retail value from 58.98% the year before.
- QR Ph count: 2.47 billion transactions, up 1,315.94% from 174.34 million in 2024, and the first year the standard outpaced debit and credit cards.
- QR Ph value: P1.16 trillion, from the same BSP measurement cycle presented in 2026 budget briefings.
Deputy Governor Zeno Ronald Abenoja tied the volume jump to InstaPay, PESONet, and person-to-merchant QR Ph. In July 2026 the central bank split the branding: QR Ph for merchant payments, InstaPay QR for person-to-person, after shoppers scanned the wrong code and paid a transfer fee.
PayMongo’s own merchant file, not a national census, shows how fast that habit moved at one processor. QR Ph was 16% of its 2025 transactions and 55% of about 10 million payments in the first half of 2026. Cards fell from 38% to 19% on that platform, and e-wallets sat at 21%. Cards still punch above their count because the average ticket is larger, which is the slice a tokenized Visa or Mastercard in Wallet is built to keep.
MRT-3 Gates Were Live Before Google Pay
Manila’s MRT-3 did not wait for Google. In July 2025 the Department of Transportation, with BSP and G-Xchange (GCash), opened an automated fare proof-of-concept on the line from North Avenue to Taft. Commuters already had three ways through a fast-lane validator months before Wallet launched.
HOW MRT-3 ALREADY TAKES A FARE
- Scan: A Commute QR or account-based ticket QR in a wallet app, including GCash, at entry and exit.
- Card tap: An EMV debit or credit card on the same validator, with no Beep-style stored-value top-up.
- Phone tap: NFC on an Android handset, including GCash Tap to Pay, using the same method to enter and leave.
GCash’s help pages warn that mixing methods on one ride fails, and that a tap-in can post a P14 hold before the true fare settles on exit, with a P28 minimum wallet balance equal to the full-line maximum fare. DOTr later said LRT-2 is in the same tap-and-scan program, with a nationwide automated fare target of 2028. In August 2026 BSP named DOTr an outstanding stakeholder for the work. Acting Secretary Giovanni Lopez framed it as cutting ticket queues.
Paymentology wrote in November 2025 that MRT-3 and modern jeepneys in Cebu were preparing for NFC tap-in and tap-out. A later launch recap said tap-and-pay was on for MRT-3 and for modern jeepneys in Cebu and Mandaue, with Easybook bus tickets in Wallet and Beep app transit still listed as future work. Maya and Visa now pitch wallet cards for public transport and tourist sites. The gate hardware was already an open-loop EMV and QR stack. Google Pay is one more token that can hit a reader that takes a chip card, not a new transit network.
Wallet’s non-payment tray filled in around that. Philippine Airlines boarding passes and other regional carriers, including AirAsia, Cathay Pacific, Jetstar, Malaysia Airlines, Singapore Airlines, Scoot, and Thai Airways, plus Trip.com bookings, can sit in the app with gate-change alerts. That is useful for flyers. It does not move a wet market QR.
Apple Pay’s Four-Bank Start
Apple Pay went live in the Philippines on August 4, 2026, with Chinabank, GoTyme, Metrobank, and UnionBank. Google Pay had a wider issuer set and a nine-month head start on Android. Apple Pay put Metrobank on tap and left several Google-live names waiting.
Limcaoco had said BPI’s cards were tokenized and ready, and that the remaining clock was Apple’s. Lito Villanueva, founding chairman of Fintech Alliance PH, had earlier said Apple delayed into the third quarter of 2026 to bring a broader bank group in. The August four-bank list shows that wait only partly worked. Google Pay remains the Android option in a market Visa pegged at roughly 80% Android.
The practical split is the phone in the customer’s hand. A Chinabank or UnionBank cardholder on iPhone taps Apple Pay. The same issuer’s Android customer uses Google Wallet. Metrobank started on Apple. EastWest, RCBC, GCash, Maya, Wise, Zed, and BPI’s debit Mastercard path were Google-first. Neither wallet creates a new clearing system. If the terminal already takes contactless cards, it already takes both.
Security Bank Pushed Both Wallets to 2027
Security Bank president and chief executive Victor Lee said in September 2026 that Apple Pay and Google Pay would not ship until the second half of 2027. “We’re changing our system, our core credit card system,” he said, and he put both wallets on the far side of that swap. Asked for a date, he said, “Both by the second half next year.”
Lee also said about 80% of the bank’s wealth clients use Apple devices, which is why Apple Pay sits in a three-year wealth plan, and he cited 1.71 million retail digital customers with about 65% active. He did not treat tap wallets as the way to win the till. He pointed at QR in Thailand and Cambodia, where banks took a larger share of everyday payments once QR was common, and at InstaPay transfers among participating banks that carry no fee.
That is the same two-track build other issuers are doing in silence. They provision Google Pay so a card can tap abroad, at an EMV gate, and on an Android phone beside Apple Pay. They still chase QR Ph because that is where the 2.47 billion transactions went in 2025. Navarro’s single-digit reading in June 2026 sits beside that pile without a contradiction. The wallet is live, the issuer list is longer than it was on November 18, 2025, and the sari-sari still wants a scan.
Security Bank will not even offer the tap layer until the second half of 2027. Until that core card system moves, its customers stay on plastic, QR, and whatever else already clears.

The Court Revisits the Climate Nuisance Door It Left Open

ChatGPT Now Compiles Live Interfaces With GPT-6

A Tanker Attack Moves the War Into Qatar’s Waters

Personio Buys Circula to Own the DATEV Channel

Bluesky Files for .bsky and Enters the Registry Queue

Microsoft’s 96% Cyber Score Sits at 86.3% on the Board

Musk’s $914 Billion Lead Is a Public SpaceX Bet

The Odyssey’s IMAX Film Run Hit a 41-Theater Limit

Free Live Sports Streaming in 2026: What to Watch Without Cable

Andrew Garfield’s Spider-Man Films Are No Longer Free
-
 NEWS3 months ago
Microsoft’s 96% Cyber Score Sits at 86.3% on the Board
-
 BUSINESS5 months ago
Musk’s $914 Billion Lead Is a Public SpaceX Bet
-
 ENTERTAINMENT3 months ago
The Odyssey’s IMAX Film Run Hit a 41-Theater Limit
-
 SPORTS4 months ago
Free Live Sports Streaming in 2026: What to Watch Without Cable
-
 ENTERTAINMENT2 years ago
Andrew Garfield’s Spider-Man Films Are No Longer Free
-
 ENTERTAINMENT4 months ago
Endgame Encore’s $86 Million Trial for Infinity Vision
-
 NEWS5 months ago
Singapore’s 3×3 and Surfing Debuts Miss the Medal Stand
-
 NEWS1 month ago
An AI Lung Drug Shifted Biological Age Clocks in Patients